HDFC Bank Ltd.'s September-quarter results were broadly in line with expectations, but brokerages remained cautious about its growth trajectory and the pace of execution. Citi cut its target price to Rs 880 from Rs 970, while JPMorgan lowered its target to Rs 970 from Rs 990. Both retained positive ratings, alongside Jefferies, Kotak Securities and Bernstein, as analysts weighed margin pressure and slower relative growth against healthy net interest income and resilient asset quality.
Net interest income rose 9.7% year on year, while net interest margin declined 10 basis points sequentially to 3.16%, largely due to the cost of mobilising FCNR-B deposits. Deposit growth was supported by FCNR-B inflows and term deposits, but CASA growth remained muted. Citi flagged constraints on the bank's relative growth trajectory, while Kotak Securities said execution remained the missing piece despite attractive valuations.
Brokerages also highlighted the possibility of a margin recovery. Management said margins were nearing a bottom and could improve as the rate cycle turns, with a 25-basis-point rate hike potentially supporting margins in Q3. However, the cost drag from FCNR-B deposits is expected to continue in the December quarter. Improving asset quality and broad-based loan growth provided support, although provisions increased sequentially.
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
HDFC Bank Q2 Highlights
Net interest income rose 9.73% year on year and 3.24% sequentially to Rs 34,619 crore from Rs 31,550 crore.
Pre-provision operating profit increased 5.58% year on year and 4.67% sequentially to Rs 29,483 crore from Rs 27,923.6 crore.
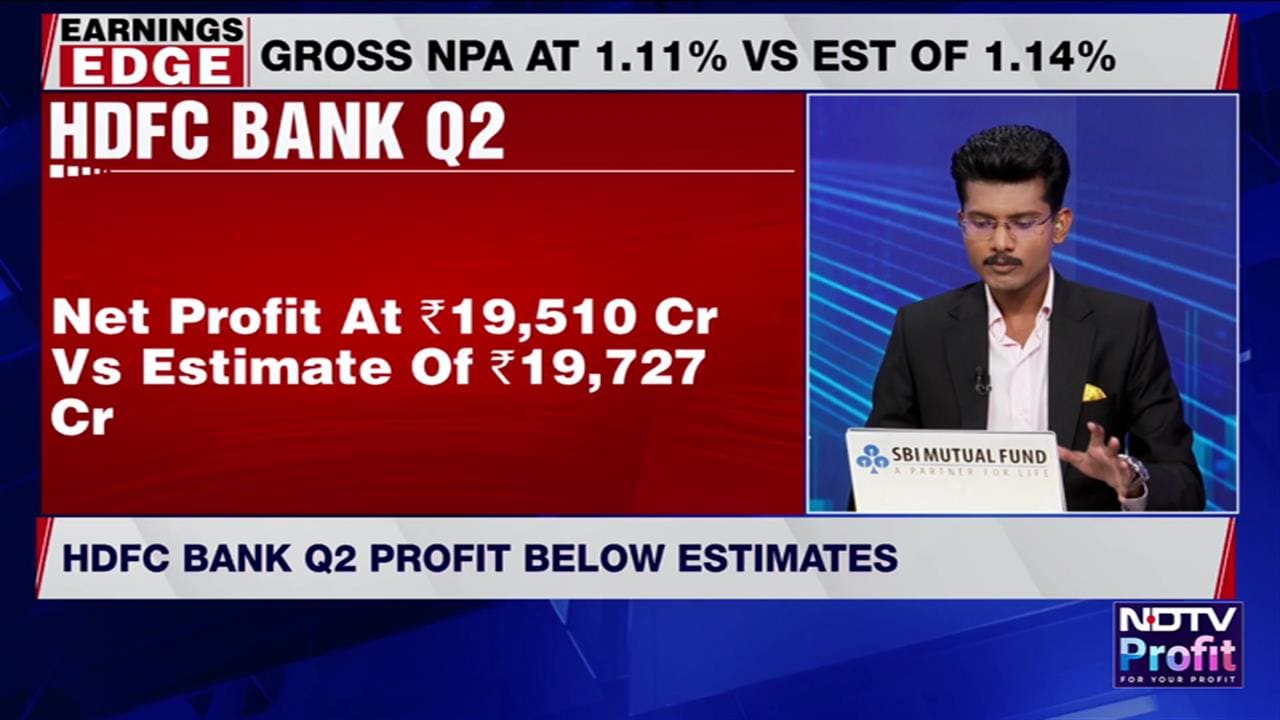
Net profit rose 4.67% year on year and 2.36% sequentially to Rs 19,510 crore from Rs 18,640 crore.
Provisions increased 16.8% sequentially to Rs 3,574 crore from Rs 3,059 crore.
Net interest margin fell to 3.16% from 3.26% in the previous quarter and 3.27% a year earlier.
Gross non-performing assets declined to 1.11% from 1.17% sequentially and 1.20% a year earlier.
Net non-performing assets fell to 0.37% from 0.41% sequentially and 0.40% a year earlier.
Loans grew 16% year on year, while deposits increased 18.8%.
READ | HDFC Bank New MD Anup Bagchi Calls For More Work On Balance Sheet, Integration Work Largely Done
Here's what brokerages are saying after HDFC Bank announced Q2 results:
Citi
Maintained 'Buy'; Target Price Cut To Rs 880 From Rs 970
Said net interest margins contracted, while growth continued to trail the banking system.
Noted that fee income supported pre-provision operating profit despite margin pressure.
Flagged limited headroom to improve the bank's relative growth trajectory.
Said asset quality remained resilient, with seasonal pressure in agriculture expected to ease.
Maintained credit costs at 46 basis points.
Highlighted execution as a key monitorable amid the leadership transition.
Jefferies
Maintained 'Buy'; Target Price At Rs 880
Said core NIMs held up better than expected.
Expects asset reallocation to support margin improvement.
Highlighted strong asset quality.
Said improving retail deposit growth and a shift towards riskier loans could support profitability.
Flagged the new chief executive and the deputy managing director's exit as potential sources of further management changes.
READ | HDFC Bank Bets On 25 Bps Hike Tailwind In Q3 As Structural Savings Shift Squeezes CASA
JPMorgan
Maintained 'Overweight'; Target Price Cut To Rs 970 From Rs 990
Described the quarter as steady and maintained a positive outlook on margins.
Said advances growth remained healthy, with retail growth picking up.
Noted that FCNR-B deposits drove strong deposit growth, while CASA growth remained muted.
Said healthy asset quality provided support to earnings.
Is awaiting details on the bank's strategic priorities.
Kotak Securities
Maintained 'Buy'; Target Price At Rs 1,050
Said the bank was entering a new phase, but familiar challenges remained.
Flagged weak treasury income as a constraint on earnings growth.
Described operating profit growth as broadly in line with expectations.
Noted that net interest income growth continued to improve, despite a 10-basis-point sequential NIM contraction, primarily due to FCNR-B deposits.
Said valuations were attractive but execution remained the missing piece.
READ | HDFC Bank Expects NIM To Improve From Q3 As Loan Repricing Kicks In
Bernstein
Maintained 'Outperform'; Target Price At Rs 1,150
Said weak earnings growth remained a concern.
Noted that loan growth was led by corporate and mid-market segments.
Highlighted healthy net interest income growth despite modest margin pressure.
Said operating expenses remained contained and asset quality continued to be resilient.
Essential Business Intelligence, Sharp Market Insights, Practical Personal Finance Advice, Daily Fuel, Gold and Silver Prices and Latest Stories — On NDTV Profit.