HDFC AMC Share Price Hits Record After Analysts Upgrade Rating, Target Price On Q2 Results
HDFC AMC's share price gained over 5% to hit record high for a second consecutive session on Wednesday as brokerages are positive on HDFC Asset Management Co. after its profit rose in the second quarter of fiscal 2025.
CLSA upgraded the stock to an 'outperform' rating from 'hold', while Nuvama and Citi raised their target prices.
The asset management company reported 32% year-on-year growth in profit after tax to Rs 576.61 crore for the three months ended Sept. 30, 2024, on a 38% rise in total income to Rs 1,058.19 crore. Analysts had estimated the net profit to be at Rs 606 crore.
Morgan Stanley, in its initial reaction to the results, said the net profit missed expectations because the tax rate was higher at 33%, as against 20% in the previous quarter and 26% in the same quarter last year—likely due to changes in the Union Budget.
The brokerage has an 'equal weight' rating on the stock, with a target price of Rs 4,120 per share, implying a downside of 9.6%. "We will follow up with a more detailed note following management commentary on the conference call at 1730 IST today," it said.
The higher tax rate was a one off and will be steady state from next quarter on, according to CLSA. The brokerage has raised its target price from Rs 4,450 apiece to Rs 4,920 per share, implying an 8% upside.
Profit excluding tax was 11% ahead of CLSA estimates and the brokerage attributed this to a beat on both AUM growth and yield expectations. "Yields expanded by 1 bps QoQ, driven by a higher share of equity mix and rationalisation of brokerages," it said. "AUM growth of 46% YoY was very strong driven by 64% YoY growth in the equity segment."
Nuvama has built in improved inflows and AUMs and accordingly increased net operating profit less adjusted taxes estimates for FY25/26/27 by 7.2%/6.7%/5.8%. Consequently, it has raised its target price to Rs 5,240 from Rs 4,910 per share earlier, while retaining a 'buy'. The new target implies upside of 15%.
Citi Research, the only brokerage with a 'sell' rating, has justified its rating as the company's "richness ignores industry headwinds and stabilising operational trends".
"While market momentum and robust operational performance has supported earnings over the past few quarters, we expect stabilisation in earnings trajectory over medium-term," it said. Industry headwinds include market fragmentation in equities, increasing direct mix for retail flows reducing proprietary distribution moats and increasing bargaining power of large and dominant distributors, Citi said.
However, it has raised its target price as it raised core profit before tax estimates by 9-10% over medium-term, largely capturing strong equity mark to market in base. The new target price is at Rs 3,600 per share from Rs 3,125 apiece.
Going ahead, CLSA said SIPs and NFOs dominate net inflows for HDFC AMC, with very strong growth in SIP inflows. "We are optimistic about the company delivering 29% AUM growth in FY25," it said.
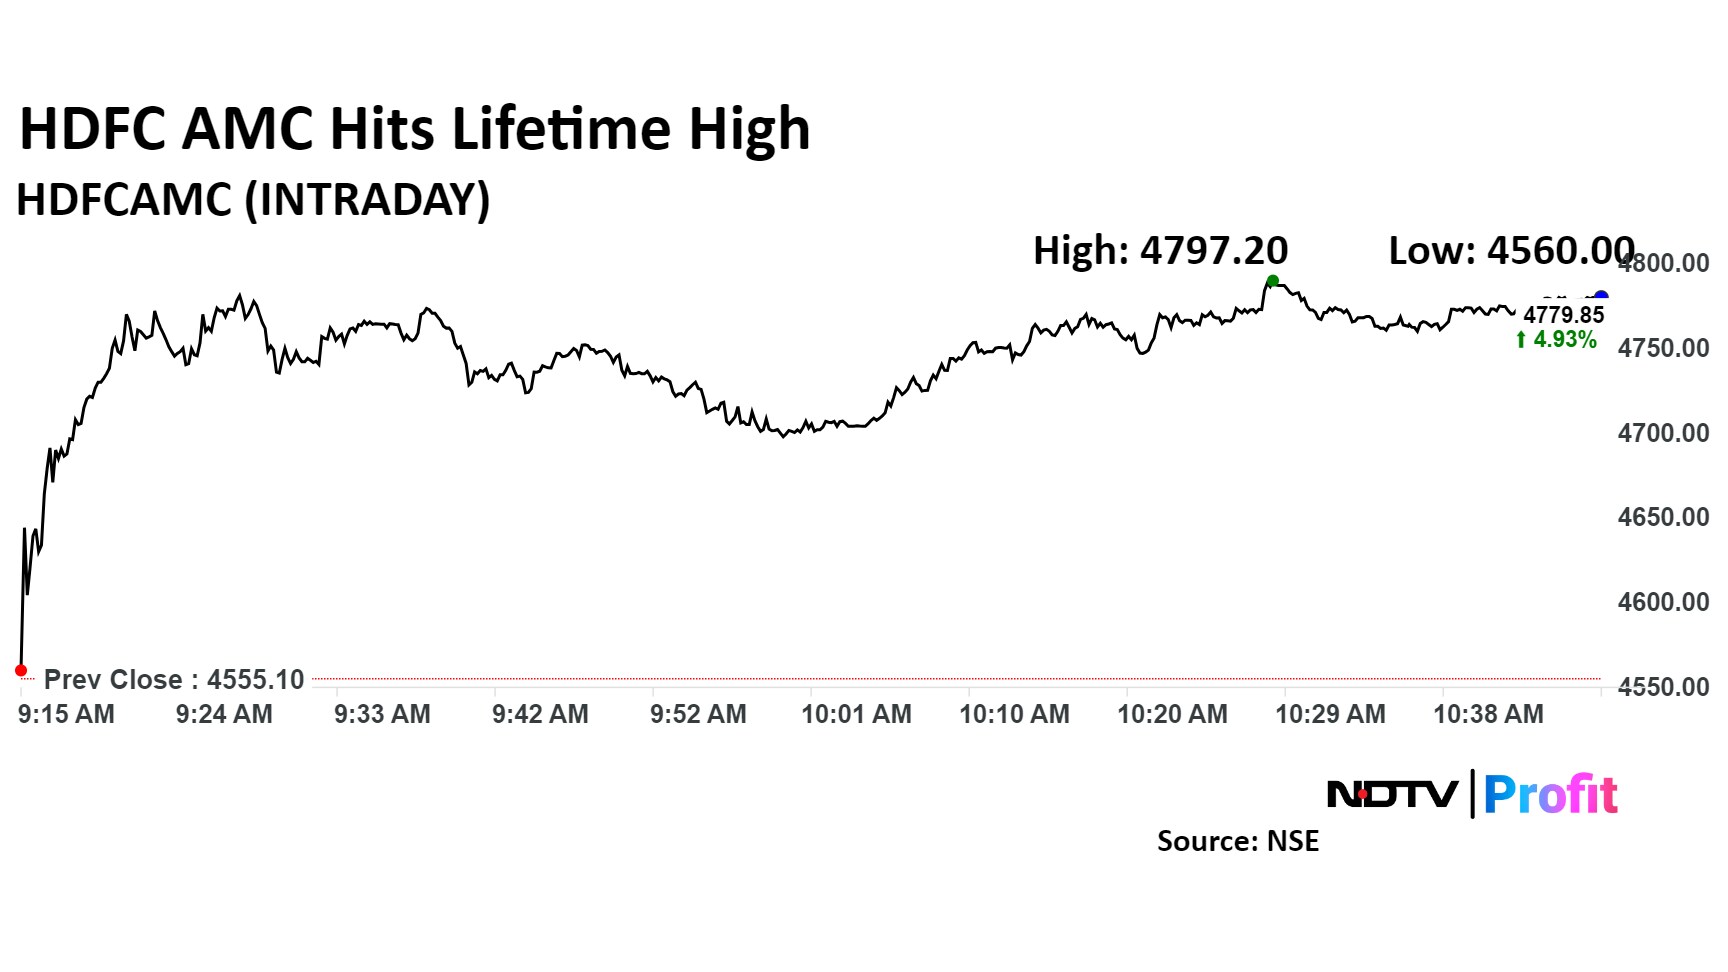
Shares of the company rose as much as 5.3% to hit a lifetime high of Rs 4,797.20 apiece. The stock gave up gains to trade 4.94% higher at Rs 4,779.90 apiece as of 10:51 a.m. This compares to a 0.12% decline in the NSE Nifty 50 index.
The stock has risen 49% on a year-to-date basis and 74.8% in the last 12 months. Total traded volume so far in the day stood at 3.03 times its 30-day average. The relative strength index was at 55.
Out of the 25 analysts tracking the company, 16 maintain a 'buy' rating, six recommend a 'hold,' and three suggest a 'sell,' according to Bloomberg data. The average 12-month consensus price target implies an upside of 1.3%.

-
High US Salaries, No Green Card Certainty: The Financial Calculation Facing Indian H-1B Families

The suspension of PERM processing at eight technology employers does not cancel existing H-1B visas. What it does is force a question many Indian families have been avoiding: is the US salary worth tying your career and family plans to one employer?
-
Swiggy vs Eternal: Food Delivery's Two Rivals Are No Longer In The Same Race
Eternal is building a private AI assistant, dark.ai. Swiggy is still working out how to make Instamart pay, with an operating loss of Rs 895 crore in the July-September quarter while Blinkit stayed profitable.
-
Where You Live Shapes How You Get To Work | The Reason Why
Two-wheelers are the most popular way to get to work in India, accounting for nearly 43% of workplace commutes.
-
Unhedged Position: Can India See An Indonesia-Style Time Correction?
The Nifty is trading below levels it first clocked in 2024. Is there, then, as I have suggested in the headline, potential that the current time correction drags on painfully for the next three-five, even ten years?
-
Navigating Friction And Energy Realities: An Analysis Of Marco Rubio's October Visit To India
Occurring at a critical juncture marked by stalled trade negotiations and escalating geopolitical pressures over global energy supplies, the visit offers a profound window into modern US-India relations.
-
India Exports Capital. Why Not Export Trusteeship?
The big question, then, is whether India can build an institution that global borrowers, investors, banks, and lawyers can trust, even without an Indian connection.
-
France's Economy & Politics Are In Crisis | The Reason Why
Let's look at how the French economy and politics evolved under Nicolas Sarkozy, Franois Hollande and Emmanuel Macron.
-
You May Inherit The Business. You Must Earn Its Credibility.
Succession tests the founder's ability to share authority as much as it tests the next generation's readiness to assume it.
-
Signing Deals Is One Thing; Making Them Work Is Another | The Week In Whys
Sometimes, things don't turn out as planned. Indian companies have lost some bids to rivals, some projects won't produce until 2030.
-
FOMC Wall, PERM Suspension, Hospital Stocks | Talking Points This Week
A PERM suspension would directly affect green-card sponsorship rather than H-1B visas, so the near-term earnings impact could remain relatively limited. The key question is whether this marks a new phase in US scrutiny of Indian IT.









