Four Reasons Why Bank Of America Merrill Lynch Is Positive On Hindalco
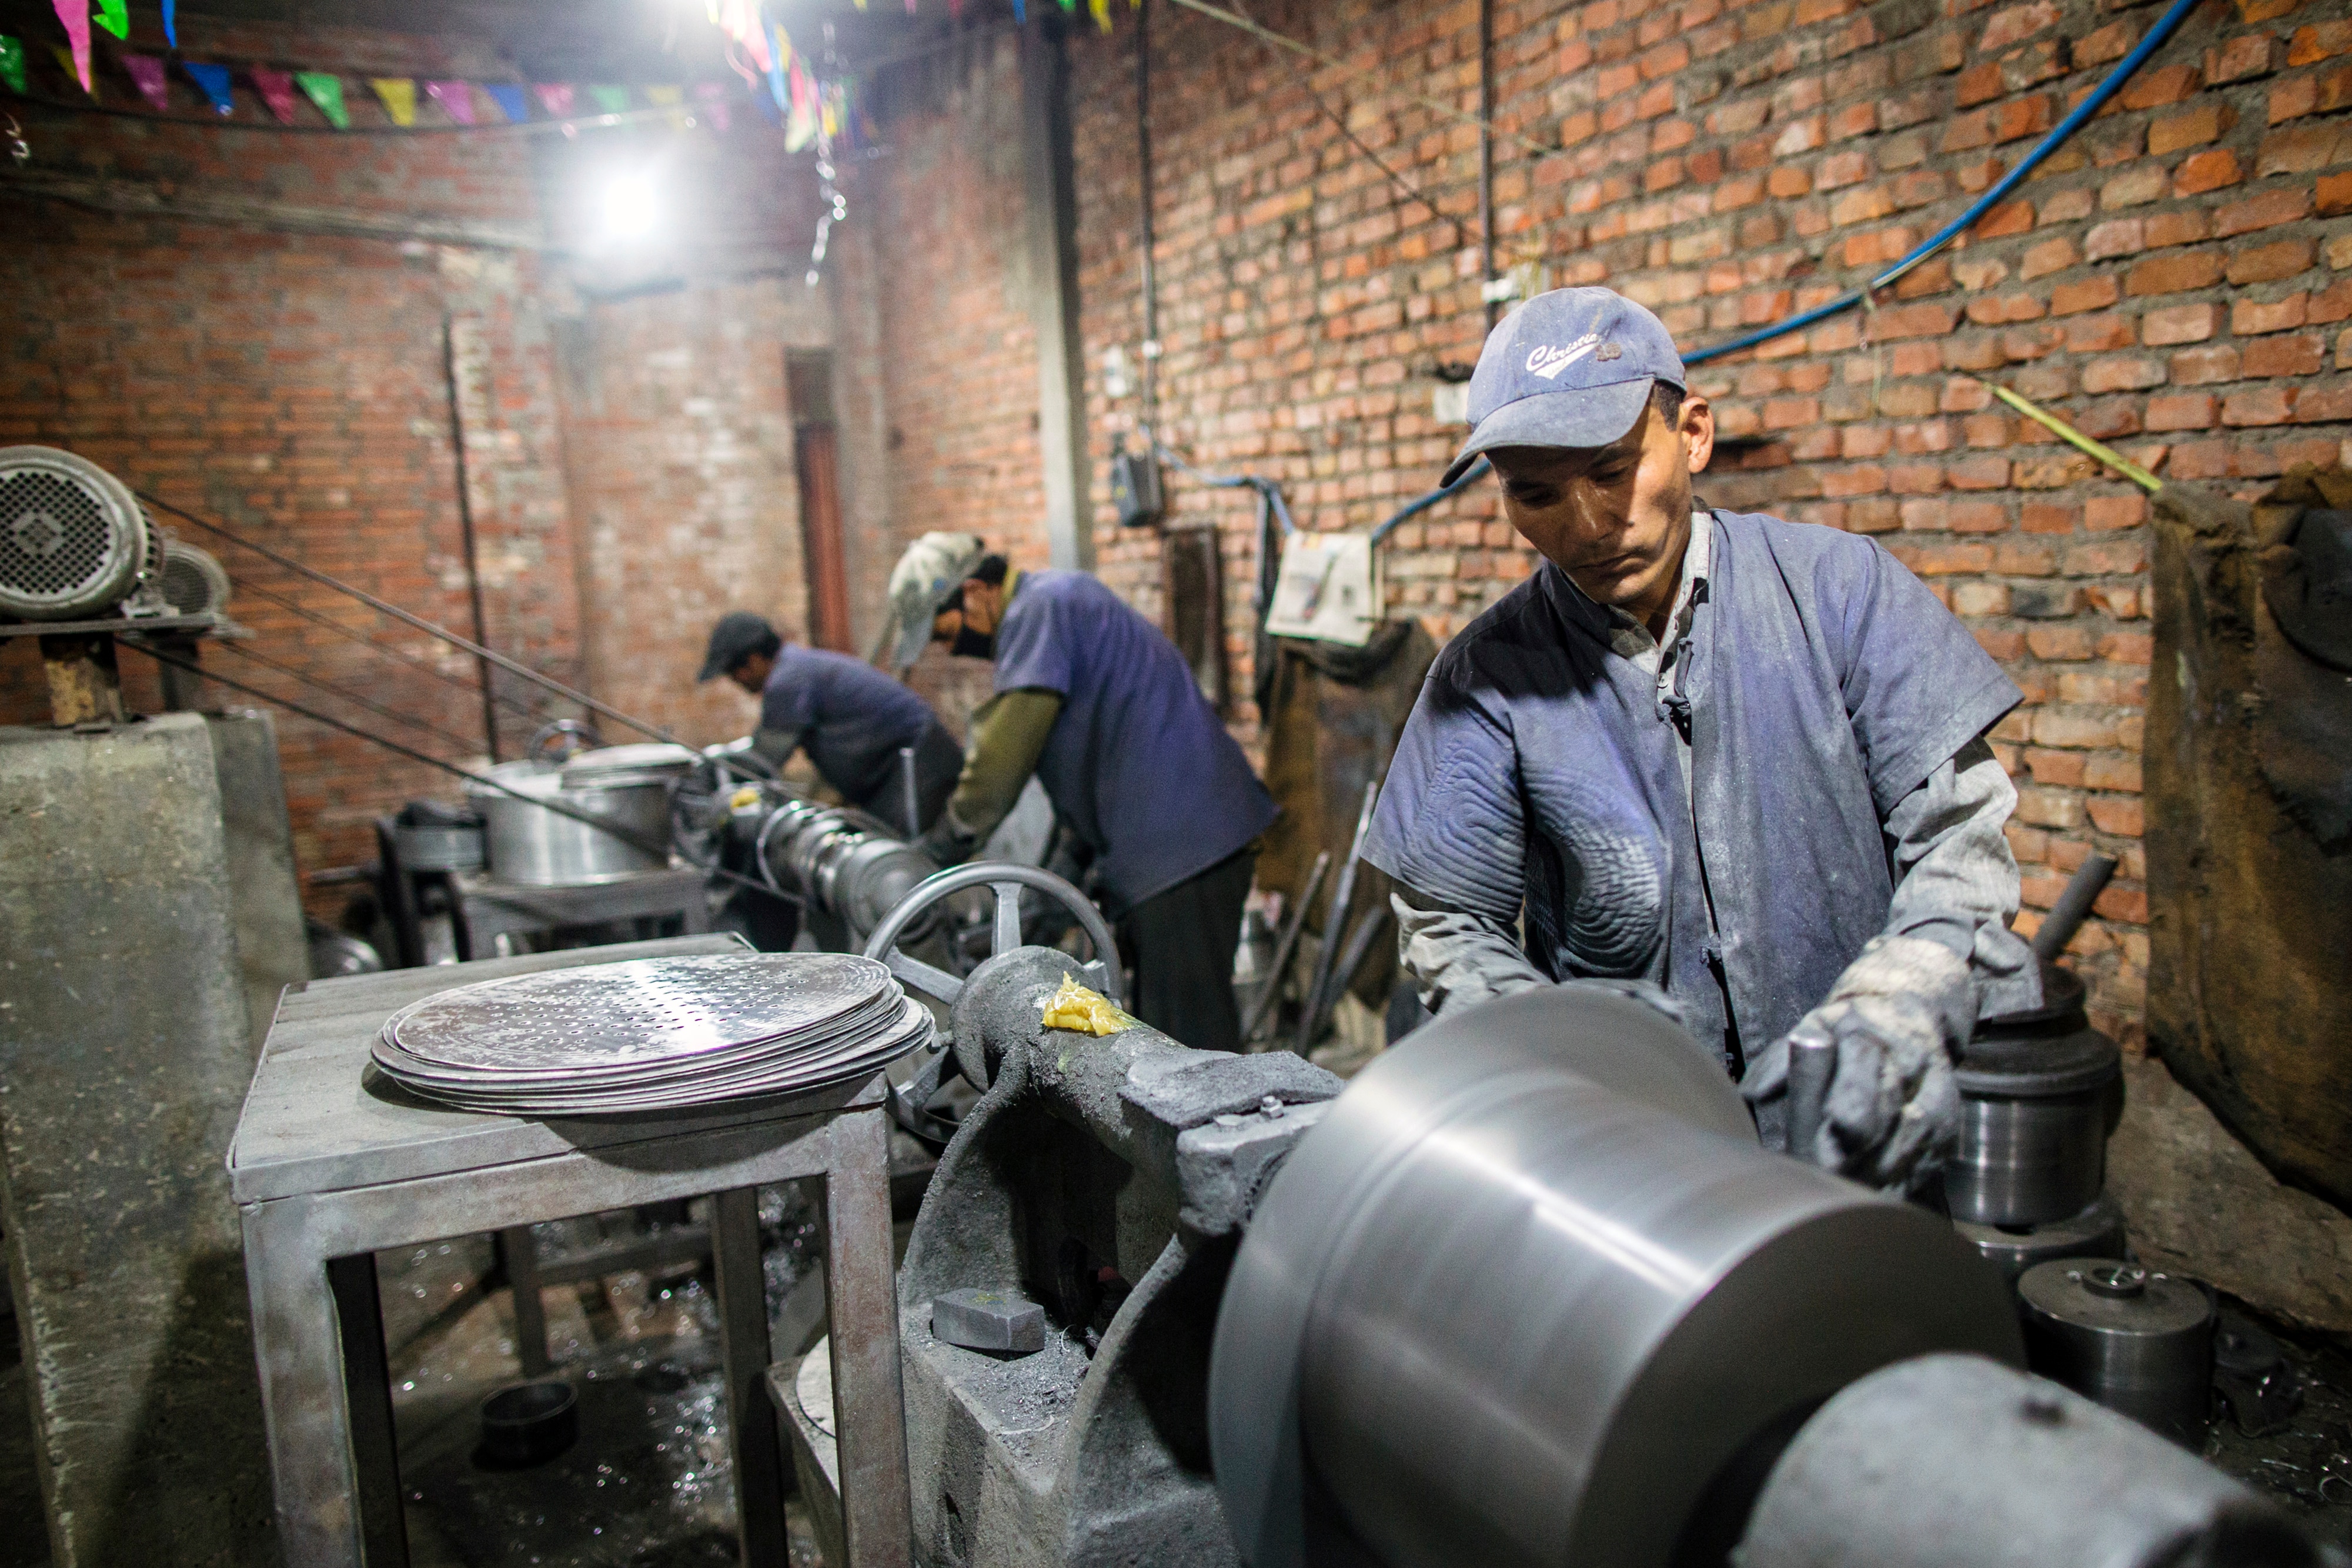
Hindalco Industries Ltd.'s globally competitive aluminium production and products businesses make it a unique bet for Bank of America Merrill Lynch.
It's the most bullish on the stock among brokerages tracked by Bloomberg. BofAML initiated coverage on Hindalco with a ‘Buy' rating and a 12-month price target of Rs 340 apiece, the highest estimate suggesting an upside potential of 22 percent from the current market price.
What makes India's largest aluminium producer attractive for the research house is:
- Improvement in costs and profitability of upstream operations.
- Widening margins of its subsidiary Novelis
- Lucrative growth in high-margin alumina business.
- Superior margins in India with entry into niche products.
BofAML said Novelis is “uniquely positioned” in global rolled products with its ability to supply advanced aluminium fibre reinforced polymers, including auto products, with production facilities in all four major industrialised continents.
It expects 17 percent expansion in the company's Ebitda per tonne over the financial years through March 2020, with contribution from high-margin auto shipments potentially rising by 700 basis points to 25 percent by March 2020. “Novelis will contribute more than 54 percent of the consolidated operating income during the period.”
Shares of Hindalco outperformed 12-month consensus forecast made at the start of 2017 by 41 percent. The stock rose for the second straight day by as much as 2.7 percent to Rs 279.4 apiece in a flat Mumbai market.

-
Why Amazon And Flipkart Are Struggling To Beat Meesho In India's Smaller Cities

With 274 million users and lowest-cost logistics, Meesho is defending its value commerce crown against giants like Amazon and Flipkart.
-
High US Salaries, No Green Card Certainty: The Financial Calculation Facing Indian H-1B Families
The suspension of PERM processing at eight technology employers does not cancel existing H-1B visas. What it does is force a question many Indian families have been avoiding: is the US salary worth tying your career and family plans to one employer?
-
Swiggy vs Eternal: Food Delivery's Two Rivals Are No Longer In The Same Race
Eternal is building a private AI assistant, dark.ai. Swiggy is still working out how to make Instamart pay, with an operating loss of Rs 895 crore in the July-September quarter while Blinkit stayed profitable.
-
Where You Live Shapes How You Get To Work | The Reason Why
Two-wheelers are the most popular way to get to work in India, accounting for nearly 43% of workplace commutes.
-
Unhedged Position: Can India See An Indonesia-Style Time Correction?
The Nifty is trading below levels it first clocked in 2024. Is there, then, as I have suggested in the headline, potential that the current time correction drags on painfully for the next three-five, even ten years?
-
Navigating Friction And Energy Realities: An Analysis Of Marco Rubio's October Visit To India
Occurring at a critical juncture marked by stalled trade negotiations and escalating geopolitical pressures over global energy supplies, the visit offers a profound window into modern US-India relations.
-
India Exports Capital. Why Not Export Trusteeship?
The big question, then, is whether India can build an institution that global borrowers, investors, banks, and lawyers can trust, even without an Indian connection.
-
France's Economy & Politics Are In Crisis | The Reason Why
Let's look at how the French economy and politics evolved under Nicolas Sarkozy, Franois Hollande and Emmanuel Macron.
-
You May Inherit The Business. You Must Earn Its Credibility.
Succession tests the founder's ability to share authority as much as it tests the next generation's readiness to assume it.
-
Signing Deals Is One Thing; Making Them Work Is Another | The Week In Whys
Sometimes, things don't turn out as planned. Indian companies have lost some bids to rivals, some projects won't produce until 2030.










