Antony Waste Aims For 20–25% Revenue Growth, Eyes Strong Margins Over Next Five Years
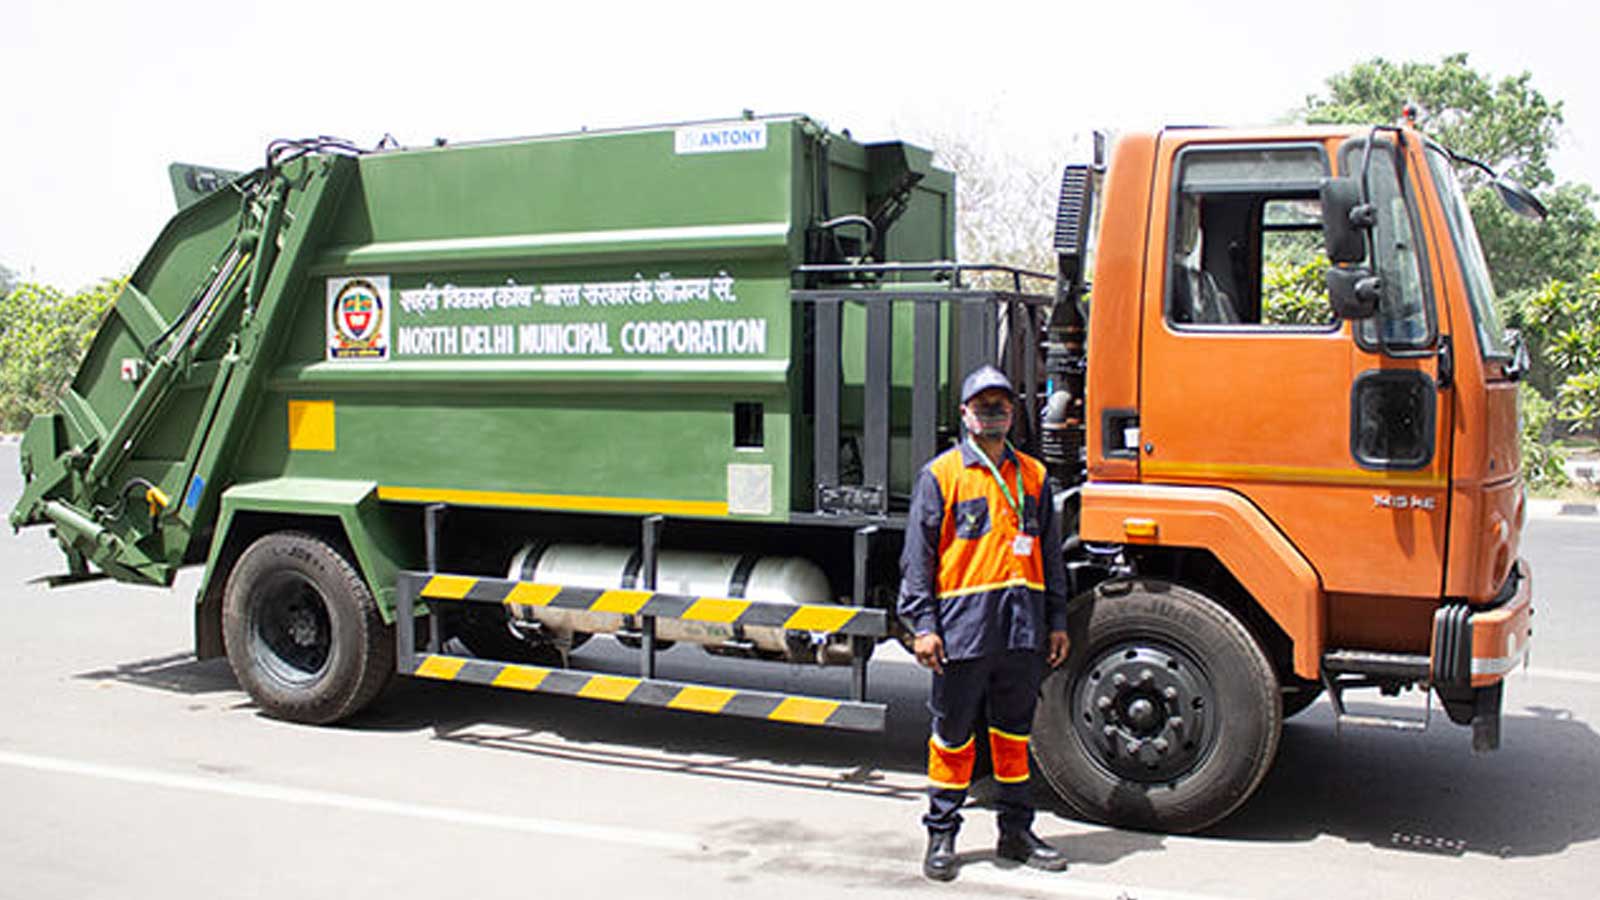
Antony Waste Handling Cell is aiming for a robust 20% to 25% compound annual growth rate (CAGR) in revenue over the next three to five years, with a projected Ebitda margin of 22% to 23%, as stated by Chief Financial Officer NG Iyer. These ambitious targets come on the heels of the company's recent strides in waste management and energy generation.
“We are in India, so waste management is a problem that is standing in our face. If I'm not able to hold on to my market share, then there is something we need to work hard on. Growth of 20% to 25% is something that should be achievable over the next three to five years. The Ebitda margin profile will be improved to at least the upper range of 23%. So we feel 22 to 23% is something that should be achieved.
CapEx is done, so the interest and depreciation extent that we're seeing today is almost capped out for us. The translation of Ebitda margin to PAT should be in the range of 9% to 11%,” Iyer said during an interview with NDTV Profit.
He pointed out that the company is witnessing robust growth prospects in Delhi, Andhra Pradesh, and Maharashtra. As of December 2024, the company had a pipeline valued at Rs 8,500 crore. “We don't see a significant addition to the bottom line of the capital employed phase unless and until we bag a significantly large contract,” Iyer added.
Antony Waste Handling Cell specialises in addressing municipal solid waste (MSW) management and converting waste to energy. These efforts help reduce reliance on fossil fuels and mitigate greenhouse gas emissions. The company is heavily involved in collection, transportation, and waste processing.
In October 2024, it secured a major contract from the Navi Mumbai Municipal Corporation for door-to-door C&T of MSW, worth Rs 908 crore. Earlier, in March 2024, it bagged a Rs 77 crore project from CIDCO for processing waste via bio-mining. Additionally, in August 2023, the company launched a waste-to-energy plant in Pimpri, Maharashtra.
Iyer also reflected on the company's financial journey over the past few years. "In 2021, our turnover was over Rs 400 crore. The current turnover should be over Rs 900 crore. So that's, like, doubling our revenue in a period which has seen Covid and delays in decision making in the risk management businesses," he said.
Antony Waste Handling Cell's current net debt stands at around Rs 390 crore, with a net debt-to-equity ratio of 0.6x, the top executive revealed.
"All my projects require CapEx to be upfront. So the CapEx that you see is already done for the existing projects for which I already signed the agreement. If I see incremental debt, that would come with new projects I may bid for," Iyer added, highlighting the company's strong liquidity and financial health.
Shares of Antony Waste Handling Cell were trading 1.41% lower at Rs 535.15 early on Wednesday, while the benchmark Nifty50 was 0.29% higher at 23,231.80 points.
Watch the full conversation here:

-
Where You Live Shapes How You Get To Work | The Reason Why

Two-wheelers are the most popular way to get to work in India, accounting for nearly 43% of workplace commutes.
-
High US Salaries, No Green Card Certainty: The Financial Calculation Facing Indian H-1B Families
The suspension of PERM processing at eight technology employers does not cancel existing H-1B visas. What it does is force a question many Indian families have been avoiding: is the US salary worth tying your career and family plans to one employer?
-
Unhedged Position: Can India See An Indonesia-Style Time Correction?
The Nifty is trading below levels it first clocked in 2024. Is there, then, as I have suggested in the headline, potential that the current time correction drags on painfully for the next three-five, even ten years?
-
Navigating Friction And Energy Realities: An Analysis Of Marco Rubio's October Visit To India
Occurring at a critical juncture marked by stalled trade negotiations and escalating geopolitical pressures over global energy supplies, the visit offers a profound window into modern US-India relations.
-
India Exports Capital. Why Not Export Trusteeship?
The big question, then, is whether India can build an institution that global borrowers, investors, banks, and lawyers can trust, even without an Indian connection.
-
France's Economy & Politics Are In Crisis | The Reason Why
Let's look at how the French economy and politics evolved under Nicolas Sarkozy, Franois Hollande and Emmanuel Macron.
-
You May Inherit The Business. You Must Earn Its Credibility.
Succession tests the founder's ability to share authority as much as it tests the next generation's readiness to assume it.
-
Signing Deals Is One Thing; Making Them Work Is Another | The Week In Whys
Sometimes, things don't turn out as planned. Indian companies have lost some bids to rivals, some projects won't produce until 2030.
-
FOMC Wall, PERM Suspension, Hospital Stocks | Talking Points This Week
A PERM suspension would directly affect green-card sponsorship rather than H-1B visas, so the near-term earnings impact could remain relatively limited. The key question is whether this marks a new phase in US scrutiny of Indian IT.
-
Everything, Everywhere, All At Once: Dalal Street's Week To Forget | Joining The Dots
Visa curbs, a Starlink spat and cancer drug caps: what connects this week's shocks for Indian markets









