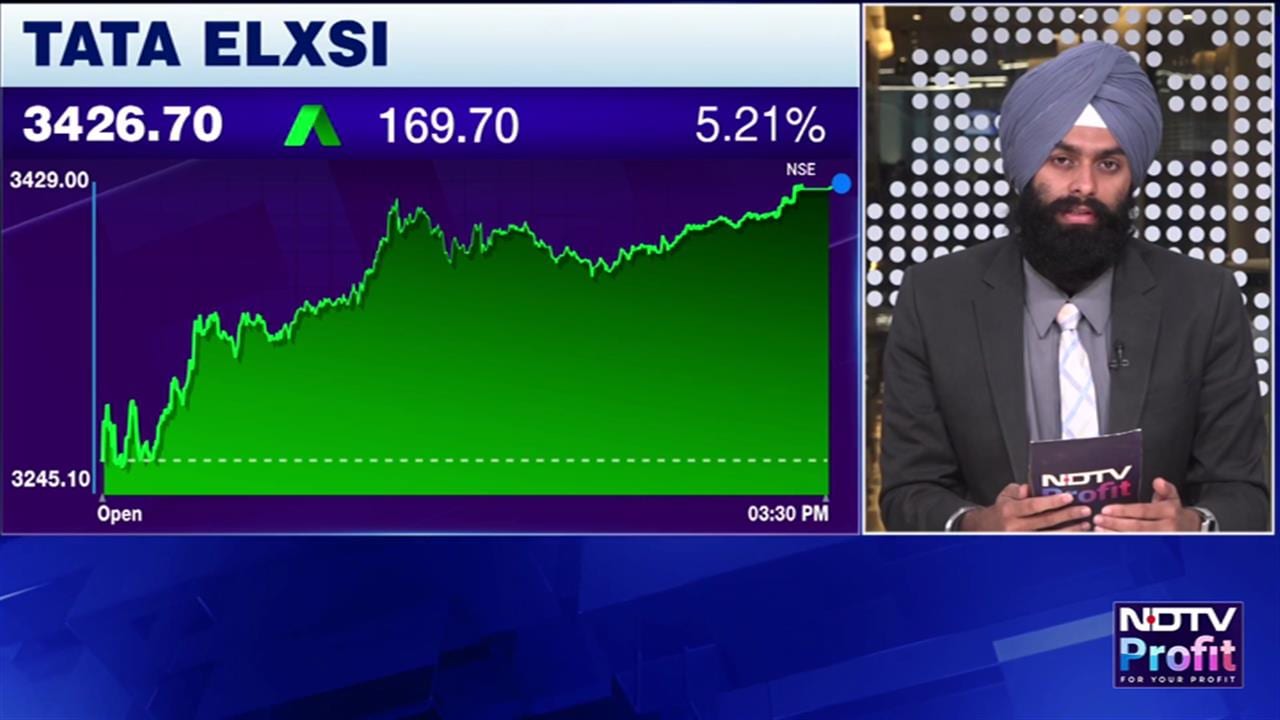
Tata Elxsi Q2 Results: Revenue Rises 3.4%, EBIT Margin Expands To 19.7%
Tata Elxsi reported mixed results for the second quarter of FY27, with constant-currency revenue rising 2.3% sequentially and operating margins expanding 70 basis points to 19.7%. Healthcare led growth across verticals, followed by media and communications. However, brokerages remain cautious about the company’s growth and profitability outlook. JPMorgan maintained its Neutral rating but cut its target price to Rs 3,200 from Rs 3,400, citing slower margin expansion and reducing earnings estimates by 10-11%. Motilal Oswal maintained its Sell rating while raising its target price to Rs 2,970 from Rs 2,790, expecting a gradual margin recovery.