Tata Communication Gets 'Buy' As JM Financial Initiates Coverage, Sees Over 35% Upside
JM Financial Institutional Securities initiated coverage on Tata Communication Ltd. with a 'buy' rating and a target price of Rs 2,030 apiece, implying a 35% upside. Tata Communications is strategically transforming into a communication technology business by developing its digital portfolio, integrating connectivity with digital services, the brokerage said.
Digital portfolio will be Tata Communication's long-term growth driver. Enterprises are transitioning fast to hyperconnected ecosystems. In this scenario, Tata Communication has posed itself as key enabler of digital transformation of enterprises, JM Financial said. For this purpose, the company is focusing more on cloud computing, security, mobility, and artificial-intelligence driven collaboration, it said.
Tata Communication has also set up an ambitious target for financial year 2027, based on digital transformation, the brokerage noted. This is achievable but with a year's delay. The reason for the delay is uncertain global macroeconomic impact on IT spendings of the company, it said.
The Tata group company aims to achieve data revenue target of Rs 28,000 crore by financial year 2027, which indicates CAGR of 33%, according to the brokerage. However, it projected 22% CAGR over financial year 2024 and 2027, factoring in the lag.
The Ebitda margin target is expected to be in the range of 23–25% by financial year 2027, which is achievable through investments, it said.
Tata Communication has its offerings divided into two broad categories: voice and data. While voice segment revenue is on a declining trend, the data segment is driving growth, as it has become increasingly relevant for connectivity needs of enterprises, the brokerage said. The data business is further categorised into core connectivity and digital portfolio. Core connectivity has continued to be the steady cash cow.
Tata Communications Share Price
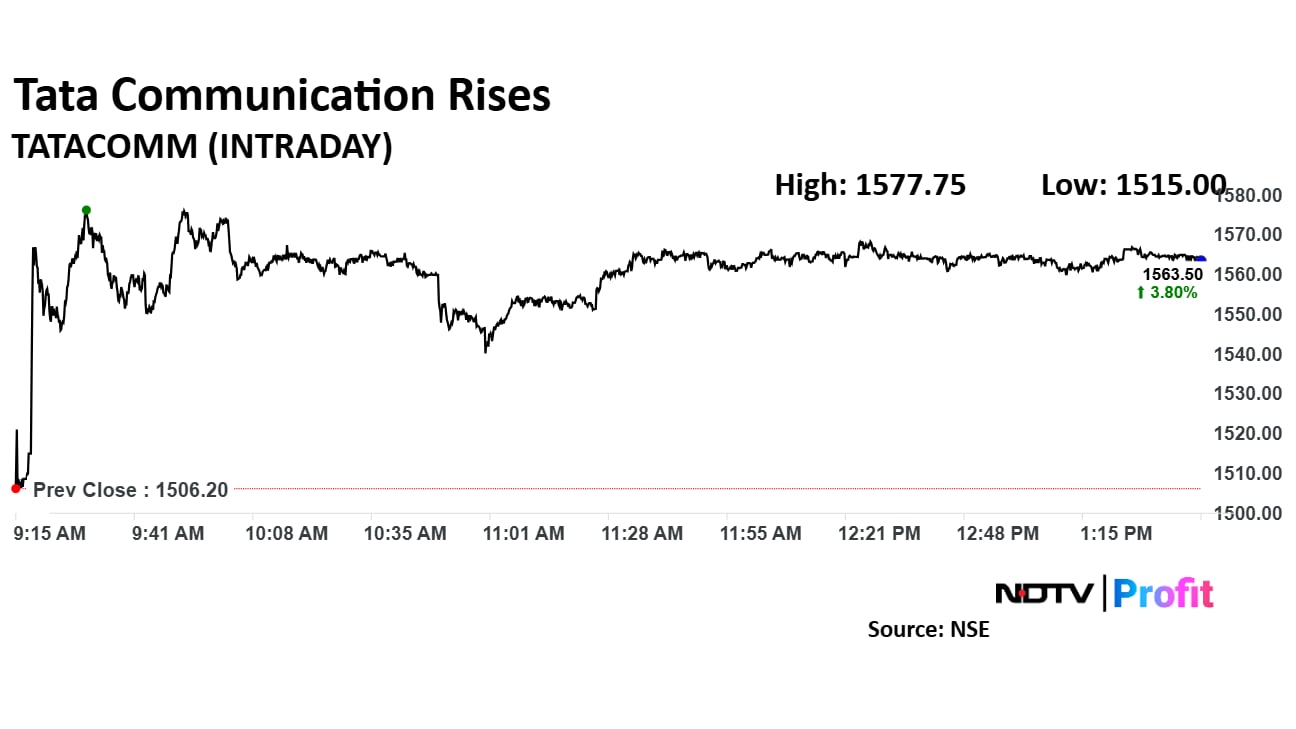
Tata Communications share price rose 4.75% to Rs 1,577.75 apiece before paring gains to trade 3.88% higher at Rs 1,564.65 apiece as of 1:39 p.m. This compared to a 0.40% advance in the NSE Nifty 50.
The stock has fallen 18.09% in 12 months, and 8.15% year-to-date. Total traded volume so far in the day stood at 3.2 times its 30-day average. The relative strength index was at 63.72.
Out of nine analysts tracking the company, six maintain a 'buy' rating, one recommends a 'hold', and two suggest 'sell', according to Bloomberg data. The average 12-month analysts' consensus price target implies an upside of 20.1%.

-
The Curious Case of Equitas Small Finance Bank And A CEO Who Quit For Stock

PN Vasudevan believes persistent investor concerns over a perceived conflict of interest had become a governance overhang on Equitas Small Finance Bank's stock, even as the lender improved profitability and asset quality.
-
Talking Points This Week: AI Cash Burn, A Tiger Comeback And An India That Still Finds Its Own Path
India is not immune to higher oil or tighter global liquidity, yet its earnings base is broader, its domestic policy levers are still available.
-
Foreign Investors Own Half Of HDFC Bank and ICICI Bank. An LTCG Cut Could Matter Most Here
Foreign portfolio investors have US$115 billion parked in HDFC Bank, ICICI Bank. If the government cuts long-term capital gains tax, Jefferies says returning foreign money could land here first.
-
'Never Seen This Level Of Negativity': Sandeep Tandon Says The Next Rally May Be Closer Than You Think
Veteran investor Sandeep Tandon says foreign selling is easing, large-caps are due a comeback and mid-caps are crowded, while he turns positive on gold, power and pharma this Diwali.
-
Indians Stay With Family, Not In Hotels | The Reason Why
India still lacks enough clean, reliable and affordable hotels for budget-conscious travellers.
-
The Economic Imperative: Analysing The Material Driving Force Behind India-Canada Strategic Reset
This economic complementarity is further reinforced by deep institutional investment ties and talent mobility, which form the bedrock of the bilateral framework.
-
Medicine Pricing: Where Must Profit Stop?
India must confront excessive margins, hidden incentives and regulatory gaps that threaten the integrity of medicine.
-
Why Amazon And Flipkart Are Struggling To Beat Meesho In India's Smaller Cities
With 274 million users and lowest-cost logistics, Meesho is defending its value commerce crown against giants like Amazon and Flipkart.
-
High US Salaries, No Green Card Certainty: The Financial Calculation Facing Indian H-1B Families
The suspension of PERM processing at eight technology employers does not cancel existing H-1B visas. What it does is force a question many Indian families have been avoiding: is the US salary worth tying your career and family plans to one employer?
-
Swiggy vs Eternal: Food Delivery's Two Rivals Are No Longer In The Same Race
Eternal is building a private AI assistant, dark.ai. Swiggy is still working out how to make Instamart pay, with an operating loss of Rs 895 crore in the July-September quarter while Blinkit stayed profitable.










