Mankind Pharma Share Price Falls After Macquarie Downgrade
Macquarie downgraded Mankind Pharma Ltd. to 'underperform' and lowered its target price on the stock as well, as the brokerage sees risks to the execution of the Bharat Serum and Vaccines acquisition, even as positives are baked in.
Share price of Mankind Pharma fell nearly 3% after receiving the downgrade.
The brokerage cut the target price to Rs 2,150 per share.
Mankind's own domestic formulations business has been weak due to slower growth in acute therapies, which accounts for up to 65% of its revenue, Macquarie said. It has included the BSV acquisition in its forecast, which adds to top-line growth, but would drag down bottom-line growth.
Domestic Formulations Business Remains Weak
The company's domestic formulations business reported a 10% growth in the first half of the financial year 2025.
Additionally, the third quarter is expected to see slower growth, with IMS IQVIA data indicating a 5% year-on-year increase. The weakness in the domestic formulations business, is attributed to the sluggish growth in acute therapies, representing up to 65% of the business.
Consequently, it has revised down the domestic formulation revenue growth CAGR to 10% from 11%.
BSV Acquisition Execution Awaited
The management anticipates strong growth and improved profitability for the BSV business in the coming years, which is reflected in the brokerage's consensus estimates as well.
However, secondary sales data from IMS IQVIA suggests BSV's sales growth is much slower, according to Macquarie.
Significant margin expansion may also be challenging due to lower gross margins and different selling channel for BSV products. It projects up to 18% revenue CAGR for BSV business in the estimates.
Exports Business Might Be Topping Out
The company's exports revenue delivered over 80% CAGR, accelerating overall top-line growth and offering operating leverage benefits.
However, recent exports data from ports suggests plateauing with Q3 exports. Hence, operating leverage benefit will be limited from hereon, according to Macquarie.
It lowered earnings estimates, primarily due to earnings dilution from the BSV acquisition. Our earnings estimates are 10% lower than Bloomberg consensus, according to the brokerage. It has cut target price by 7% to Rs 2,150 per share, based on 30 times price to earnings ratio.
"We use cash EPS to adjust for meaningful amortisation drag on reported earnings from the recent acquisition of BSV. Mankind's revenue is projected to deliver an 18% CAGR, mainly due to the BSV acquisition, while its core business slows. Acquisition-related debt and amortisation will limit net profit CAGR to 14%. At a 38 times PER on FY27 earnings, stock price reflects potential gains but overlooks risks," according to the brokerage.
Mankind Pharma Share Price
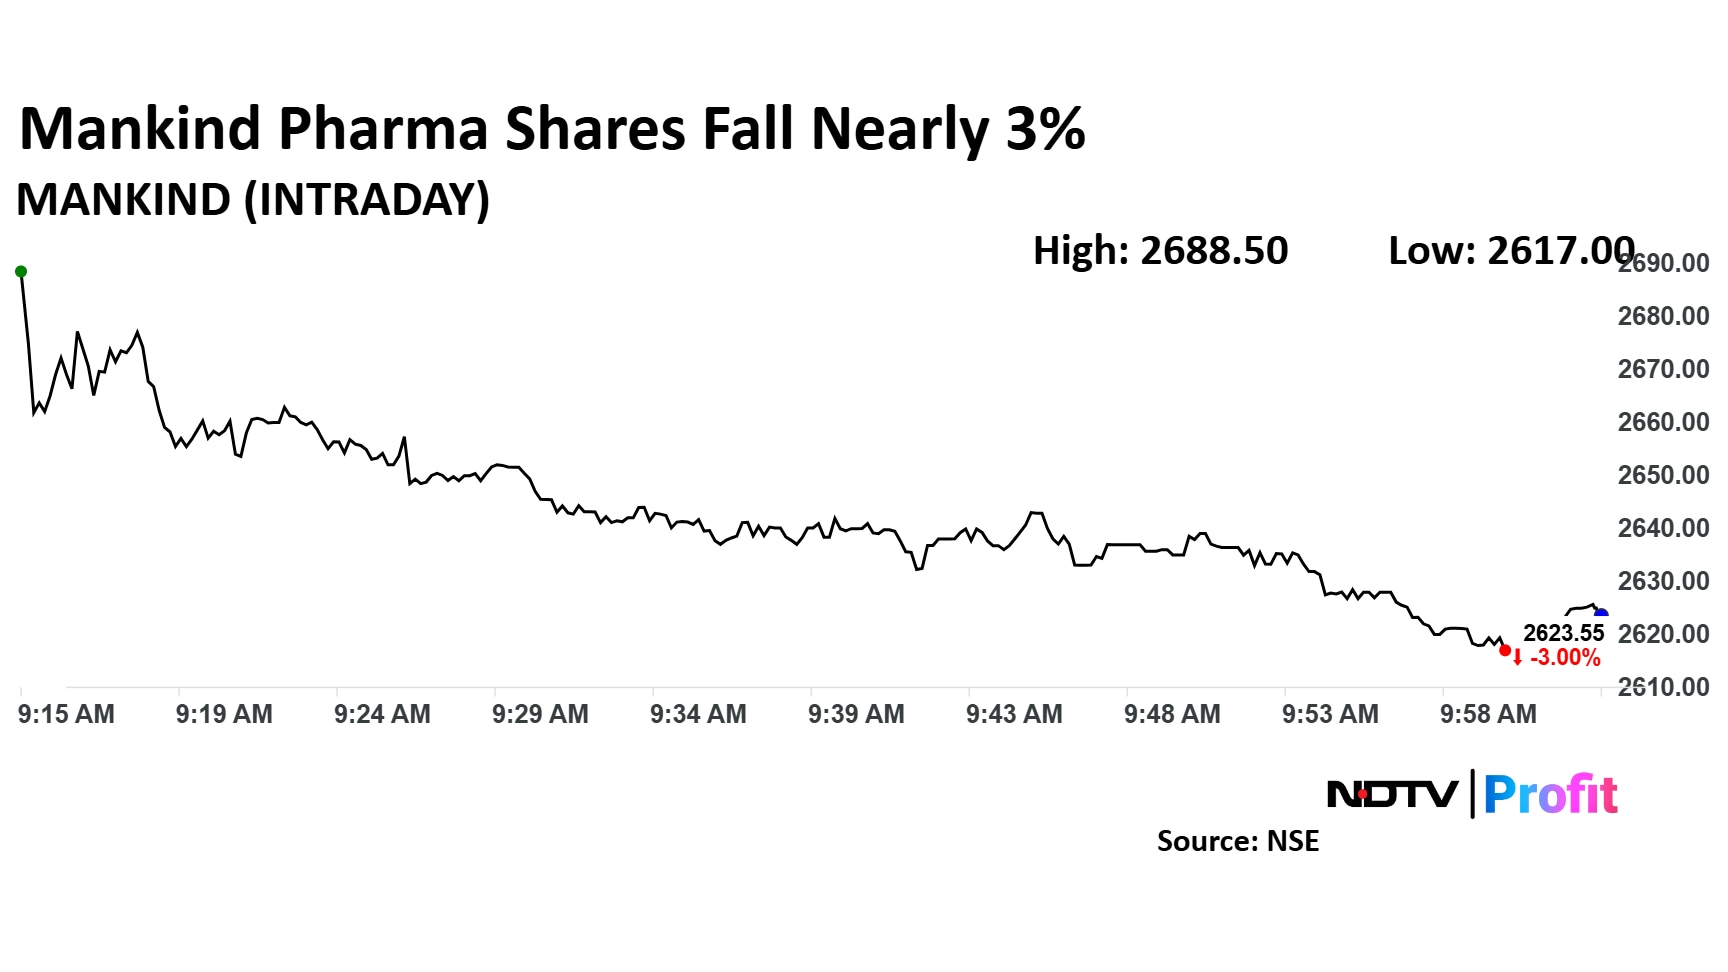
Mankind Pharma Ltd. stock fell as much as 3.31% during the day to Rs 2,615 apiece on the NSE. It was trading 2.97% lower at Rs 2,624.3 apiece, compared to a 0.78% decline in the benchmark Nifty 50 as of 10:34 a.m.
It has risen 22.32% in the last 12 months. The total traded volume so far in the day stood at 0.8 times its 30-day average. The relative strength index was at 43.27.
Of the 16 analysts tracking the company, 12 have a 'buy' rating on the stock, two recommend a 'hold' and two suggest a 'sell', according to Bloomberg data. The 12-month analysts' consensus target price on the stock is Rs 2,883, implying an upside of 9.4%.

-
India's Troika Of Good Luck | Joining The Dots

A weaker Trump, a cooling AI trade and resilient earnings have put Indian markets back in favour. Rising inflation could spoil the party.
-
Talking Points This Week: Leadership Shock At Nvidia, Earnings Strength, And The Fog Over Hormuz
The Anthropic IPO pricing and first trading day, Nvidia's upcoming earnings, and any fresh signals from Iran will set the tone for the following week.
-
Signature Play: The Classic Cocktail Is Dead. Or Is It?
Classic cocktails are disappearing from India's cocktail menus. But they're still being ordered, taught to bartenders and borrowed from. So, who's really having the last drink?
-
A New Samvat Wishlist: Inclusive Prosperity And Human Development
India has strengthened its economic foundations through infrastructure, digital access and enterprise. Its next growth chapter must deepen productivity, create better livelihoods and widen participation in prosperity.
-
Love, Sex Aur Dhokha: The Audacious Plot To Spy On Jensen Huang
A Taipei dinner, a Singapore chip buyer and a suspected Chinese asset: inside the alleged spy operation that got close to NVIDIA's Jensen Huang.
-
Ten Things I Learnt This Samvat
Patience can be a trap. Cheap stocks can stay cheap. Leverage can wipe you out. What did Samvat 2082 teach us? Niraj Shah writes on 10 lessons from the year gone by.
-
Talking Points This Week: Tech Nerves, FII Buying, And A Faraway Banking Shock
The global markets are not shining this Diwali. The exception in the large markets is, India.
-
Midterm Rally Lasted A Day. The Hard Reality Of A Divided US May Last Two Years | Opinion
Between a contested AI boom, a debt ceiling that arrives in 2027 and a president with every incentive to act alone, the next two years may prove more volatile than the first day's rally suggests.
-
Blue Wave Will Derail the AI Trade but Won't Dismantle the AI Era | Unhedged Position
The Democrats' sweep of the US Congress will see politics collide with economic forces both over the long and short term.
-
It's Time To Take The GST Council's Bet On Trust Global
Payment records can prove India's services exports, and clear, proportionate rules can bring foreign digital sellers into the tax net.









