Jubilant Pharmova Gets 'Buy' As Nuvama Initiates Coverage, Sees Stock Gaining 30%
Nuvama Insitutional Equities initiated coverage on Jubilant Pharmova Ltd. with a 'buy' rating and estimated the stock price to gain over 30%. The brokerage has a target price of Rs 1,450 per share, implying a 30.40% upside from Friday's closing price.
Jubilant Pharmova is embarking on a new earning cycle with several growth factors at play, said Nuvama Insitutional Equities in a note on Monday. The brokerage expects the company's revenue and operating profit to grow at a CAGR of 11% and 24%, respectively.
Ruby–Fill ramp up, turn around in radio pharmacy and generic businesses, and commissioning of Line–Spokane, and contract research organisation growth will help Jubilant Pharma drive the estimated revenue and Ebitda growth, according to Nuvama. The brokerage sees growth visibility of $350 million beyond financial year 2027 and financial year 2030.
The real booster shot would be balance sheet improvement and is likely to raise net profit 4 times over financial year 2023–24, and 2026–27, the brokerage said in the note. Jubilant Pharmova may generate free cash flow of Rs 1,900 crore between financial year 2025 and 2027, as its improvement of profit and loss statement will help repay debt and raise its return on capital employed to 14% by fiscal 2027.
"Besides potential tailwinds in the wake of the Biosecure Act in the CRO business, product launches in generics may unlock further potential upside to revenue in our estimates," Nuvama said.
Growth Drivers
Nuvama Institutional Equities observed that the commoditised business of Jubilant Pharma have potent growth drivers such as launches, fresh capex coming on stream and industry tailwinds.
Jubilant Pharmova's Radio Pharma business is expected to benefit from Ruby-Fill ramp-up, and I-MIBG launch. While its allergy business will take advantage of ex–US market growth, the brokerage said.
As far as its contract developing and manufacturing organisation is concerned, it will grow on the back of industry normalisation and capex getting completed in fiscal 2027, the brokerage said.
Jubilant Pharmova's generic business will grow due to new launches and compliance reinstatement at Roorkee facility, according to Nuvama.
Jubilant Pharmova Share Price
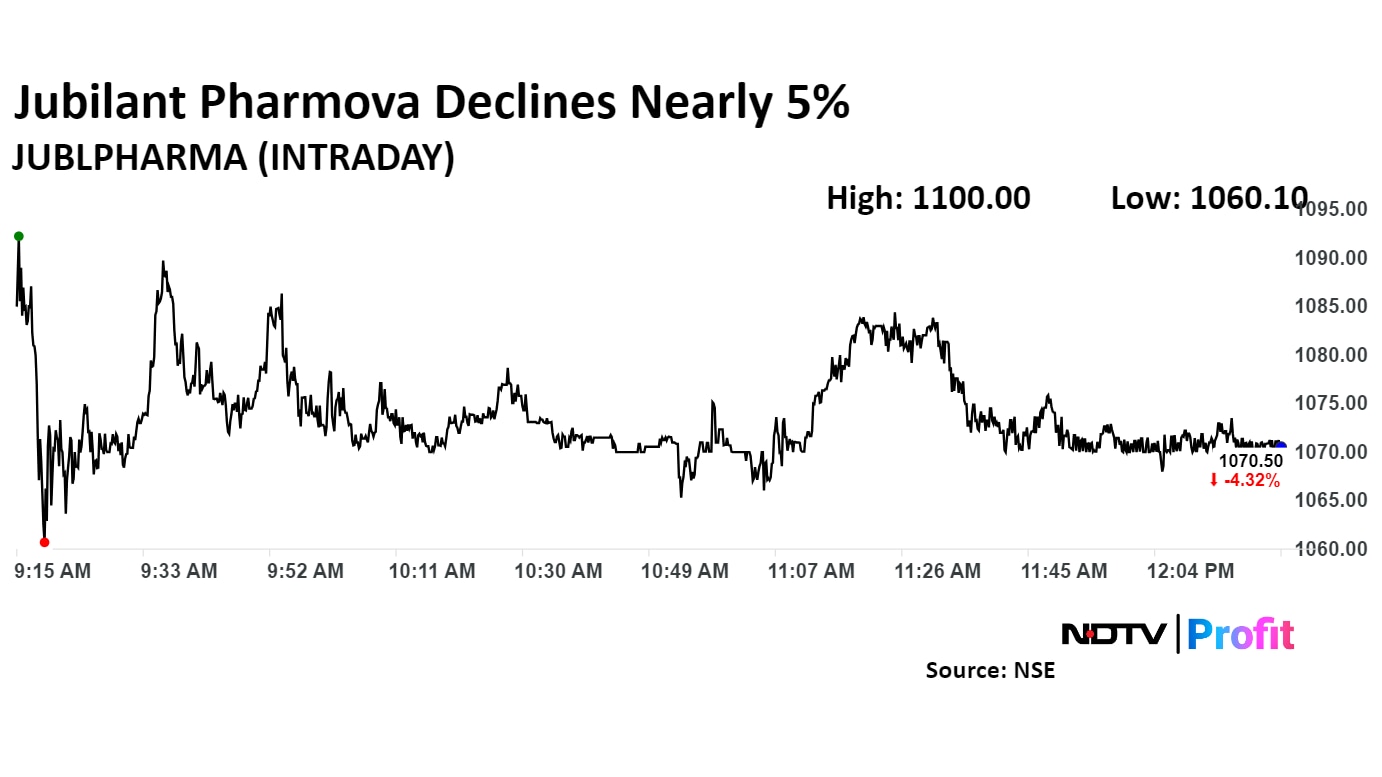
Jubilant Pharmova Ltd.'s share price declined 4.66%, the lowest level since Oct. 4., before paring loss to trade 3.77% lower at Rs 1,070.05 per share as of 12:20 p.m. This compares to 0.45% decline in the NSE Nifty 50.
The stock has risen 150.60% in 12 months, and 96.32% year-to-date. Total traded volume so far in the day stood at 0.06 times its 30-day average. The relative strength index was at 47.31.
Two analysts tracking the company maintain a 'buy' rating, according to Bloomberg data. The average 12-month analysts' consensus price target implies an upside of 17.5%.

-
High US Salaries, No Green Card Certainty: The Financial Calculation Facing Indian H-1B Families

The suspension of PERM processing at eight technology employers does not cancel existing H-1B visas. What it does is force a question many Indian families have been avoiding: is the US salary worth tying your career and family plans to one employer?
-
Swiggy vs Eternal: Food Delivery's Two Rivals Are No Longer In The Same Race
Eternal is building a private AI assistant, dark.ai. Swiggy is still working out how to make Instamart pay, with an operating loss of Rs 895 crore in the July-September quarter while Blinkit stayed profitable.
-
Where You Live Shapes How You Get To Work | The Reason Why
Two-wheelers are the most popular way to get to work in India, accounting for nearly 43% of workplace commutes.
-
Unhedged Position: Can India See An Indonesia-Style Time Correction?
The Nifty is trading below levels it first clocked in 2024. Is there, then, as I have suggested in the headline, potential that the current time correction drags on painfully for the next three-five, even ten years?
-
Navigating Friction And Energy Realities: An Analysis Of Marco Rubio's October Visit To India
Occurring at a critical juncture marked by stalled trade negotiations and escalating geopolitical pressures over global energy supplies, the visit offers a profound window into modern US-India relations.
-
India Exports Capital. Why Not Export Trusteeship?
The big question, then, is whether India can build an institution that global borrowers, investors, banks, and lawyers can trust, even without an Indian connection.
-
France's Economy & Politics Are In Crisis | The Reason Why
Let's look at how the French economy and politics evolved under Nicolas Sarkozy, Franois Hollande and Emmanuel Macron.
-
You May Inherit The Business. You Must Earn Its Credibility.
Succession tests the founder's ability to share authority as much as it tests the next generation's readiness to assume it.
-
Signing Deals Is One Thing; Making Them Work Is Another | The Week In Whys
Sometimes, things don't turn out as planned. Indian companies have lost some bids to rivals, some projects won't produce until 2030.
-
FOMC Wall, PERM Suspension, Hospital Stocks | Talking Points This Week
A PERM suspension would directly affect green-card sponsorship rather than H-1B visas, so the near-term earnings impact could remain relatively limited. The key question is whether this marks a new phase in US scrutiny of Indian IT.









