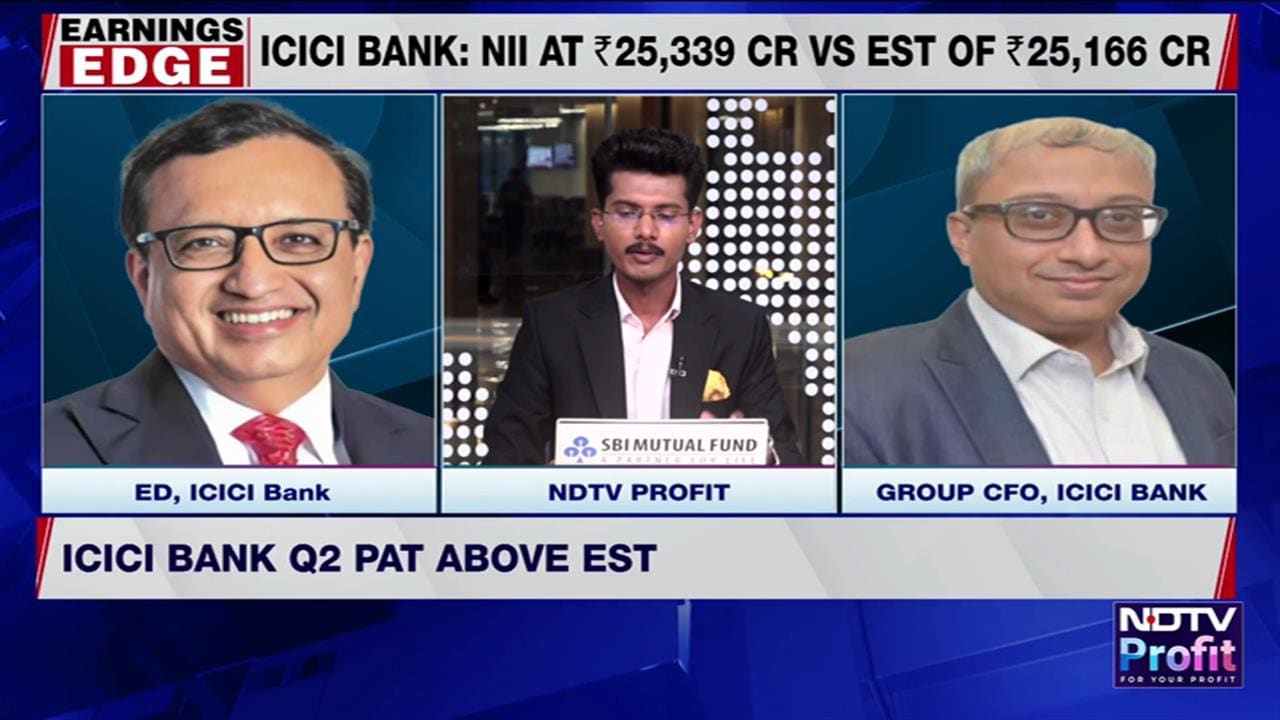
Shares of ICICI Bank gained, while those of HDFC Bank and Axis Bank declined by up to 4% in early trade on Monday, as investors assessed the September-quarter earnings of the three largest private sector lenders.
ICICI Bank shares rose as much as 1.08% to Rs 1,412 apiece on the BSE. HDFC Bank shares fell as much as 1.53% to Rs 716.90, while Axis Bank declined 4.07% to Rs 1,234. The Bank Nifty index was down 0.57%, with Axis Bank emerging as one of its top losers.
The three lenders reported their Q2FY27 earnings on October 17, with each outperforming its peers on at least one key financial metric.
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
HDFC Bank reported the highest net profit among the three lenders, although its growth was relatively modest. ICICI Bank recorded the highest net interest margin (NIM) and the strongest growth in net interest income, while Axis Bank posted the fastest growth in net profit, supported by a decline in provisions and a favourable base effect.
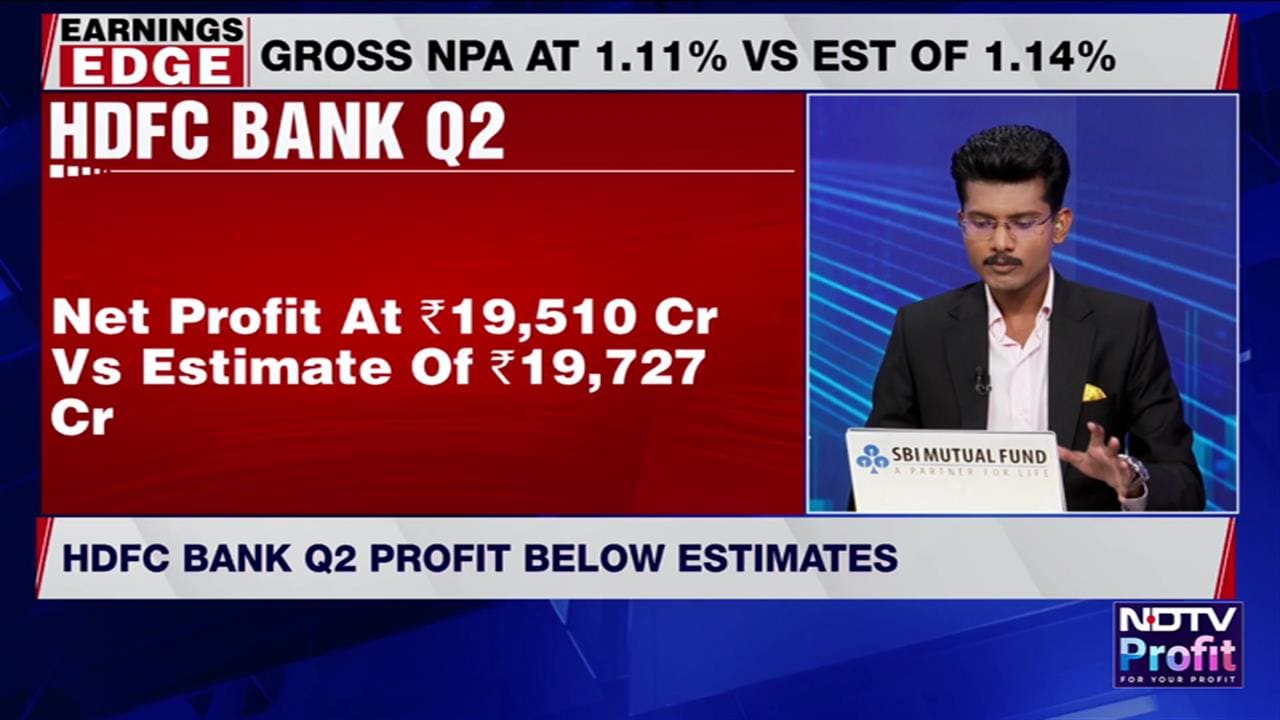
HDFC Bank's standalone net profit rose 4.7% year-on-year (YoY) to Rs 19,510 crore in Q2FY27, supported by treasury income. ICICI Bank's net profit increased 20.1% YoY to Rs 14,843 crore, while Axis Bank's bottom line surged 37.6% YoY to Rs 7,003 crore.
ALSO READ: Axis Bank Vs HDFC Bank Vs ICICI Bank Q2 Results: Who Led On Profit, Margins And Bad Loans?
However, all three lenders reported a sequential contraction in net interest margins, partly due to the mobilisation of foreign-currency deposits under Reserve Bank of India's FCNR(B) swap window.
ICICI Bank's NIM declined to 4.18% in the September quarter from 4.36% in the June quarter and 4.30% a year earlier. HDFC Bank reported a NIM of 3.32%.
Axis Bank witnessed the sharpest contraction in NIM among the three lenders, with the metric falling to 3.36% from 3.46% in the previous quarter and 3.73% a year earlier. The bank said FCNR(B) deposits alone reduced its NIM by 11 basis points. Excluding this impact, its NIM would have stood at 3.47%.
Axis Bank shares came under greater pressure as investors weighed the lender's weaker performance on key operating metrics against its peers, despite healthy business growth, improved asset quality and lower operating expenses as a proportion of assets. The bank has continued to face pressure on its NIM, raising concerns about its ability to arrest the decline in core profitability.
Analysts have also flagged risks to Axis Bank's fee income from the Insurance Regulatory and Development Authority of India's (IRDAI) consultation paper on commission caps.
Brokerage firm Motilal Oswal Financial Services believes that ICICI Bank is well poised to deliver 2.34% and 2.38% RoA over FY27 and FY28. Asset quality is among the one of the best in the industry while healthy contingency buffer at Rs 131 billion (0.7% of loans) provides comfort.
ALSO READ: ICICI Bank Q2 Review: FCNR Gains Boost Balance Sheet, Says IDBI Capital; Check Target Price
The brokerage firm raised its earnings estimates by 3% for FY28, expecting RoA and RoE of 2.4% and 17.6%. ICICI Bank remains Motilal Oswal's top ‘Buy' in the sector with a target price of Rs 1,750 apiece.
For HDFC Bank, the brokerage firm believes the improvement in NIMs from retirement of high-cost borrowings and operating leverage should support a gradual improvement in profitability and return ratios in the coming years.
It raises FY27 and FY28 earnings estimates by 3.5% each and estimates HDFC Bank to deliver FY28 RoA and RoE of 1.74% and 14.1%.
Motilal Oswal reiterated its ‘Buy' call on HDFC Bank shares with a target price of Rs 925 apiece.
Axis Bank reported a mixed quarter, with strong NII growth and lower provisions offset by elevated opex. It continues to maintain a healthy cumulative provision buffer of Rs 159 billion (~1.2% of loans), which is expected to facilitate a smooth transition to the ECL framework, Motilal Oswal noted.
The brokerage raised its FY28E earnings estimate by ~5%, factoring in rate hikes, taking FY28E RoA and RoE to 1.6% and 15.1%. It reiterated ‘Neutral' call on Axis Bank shares with a target price of Rs 1,475 apiece.
ALSO READ: Catch Stock Market Live Updates Here
Disclaimer: The views and opinions expressed by the investment advisers on NDTV Profit are of their own and not of NDTV Profit. NDTV Profit advises users to consult with their own financial or investment adviser before taking any investment decision.
Essential Business Intelligence, Sharp Market Insights, Practical Personal Finance Advice, Daily Fuel, Gold and Silver Prices and Latest Stories — On NDTV Profit.