Hyundai Motor India Receives 'Outperform' Rating With Target Price Hike From CLSA—Here's Why
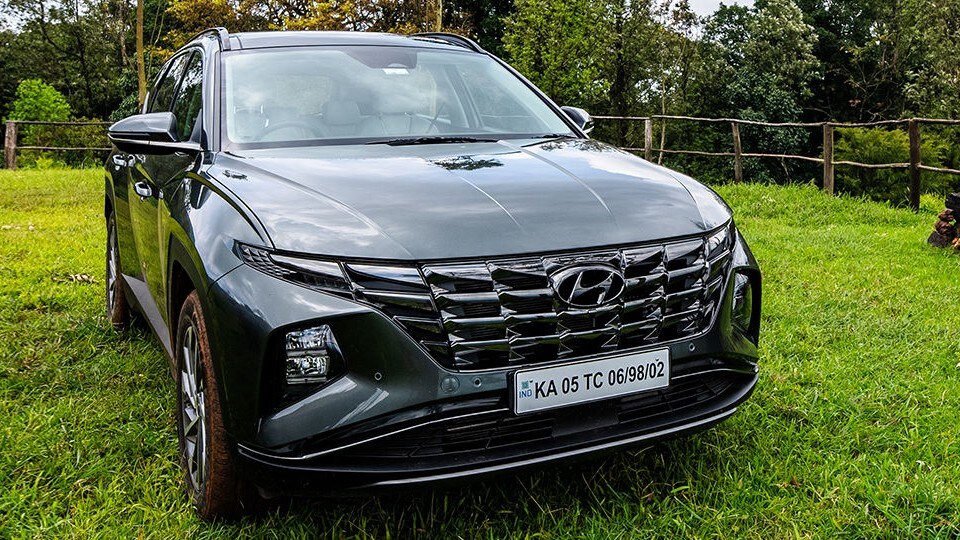
Hyundai Motor India Ltd. has been assigned an "Outperform" rating with a target price hike by CLSA. The brokerage initiated coverage on the company with a discounted cash flow (DCF)-based target price of Rs 2,155, implying a 24x multiple on FY27CL earnings per share (EPS), in line with the target valuation of market leader Maruti Suzuki India Ltd.
The company's strategy revolves around targeting the aspirational class through an affordable and diversified portfolio, with a current mix of 63% in Utility Vehicles (UVs). Despite facing market share erosion, the launch of new models and capacity expansion from its Talegaon plant, set to go live in financial year 2026, are expected to fuel growth from financial year 2027 onwards.
CLSA's report highlighted Hyundai's competitive advantage in unit economics, which it considers superior to that of Maruti Suzuki. This positions Hyundai Motor to regain market share once the Talegaon facility comes online. Additionally, the upcoming launch of the e-Creta, an affordable electric vehicle (EV), is seen as a significant step toward strengthening Hyundai's EV portfolio.
Hyundai has struggled with a loss of UV market share and is largely dependent on models like the Creta in UV segment (which accounts for 45% of HMIL's UV sales); CLSA believes the company must reduce its dependence on the Creta and introduce higher-priced SUVs in the Rs 20 Lakh+ segment, such as the XUV700 and Harrier. This is expected to become a focus once the new plant is operational in FY26.
Hyundai's revenue and earnings have underperformed recently, particularly in the compact and mini segments. However, the firm is set to meet the Corporate Average Fuel Economy (CAFE) standards by FY28, with a growing mix of CNG and EV vehicles. CLSA forecasts that Hyundai Motor will maintain an Ebitda margin of around 13% from FY25-27, despite rising fixed costs and a higher royalty rate. Cost control measures and a disciplined pricing strategy are anticipated to support profitability.
The brokerage also estimates that Hyundai will continue to make significant capital investments, with annual capex expected to reach Rs 3,000 crore in FY26-27. As a result, the company is projected to offer a free cash flow yield of about 3.4% in FY27.
While CLSA remains positive on Hyundai Motor's long-term growth prospects, the report acknowledges risks, including subdued growth in the domestic PV market, increasing competition, and rising royalty costs. Despite these challenges, the brokerage expects Hyundai to deliver a 10% revenue growth and 13% earnings compound annual growth rate (CAGR) from FY25 to FY27.

-
India's Troika Of Good Luck | Joining The Dots

A weaker Trump, a cooling AI trade and resilient earnings have put Indian markets back in favour. Rising inflation could spoil the party.
-
Talking Points This Week: Leadership Shock At Nvidia, Earnings Strength, And The Fog Over Hormuz
The Anthropic IPO pricing and first trading day, Nvidia's upcoming earnings, and any fresh signals from Iran will set the tone for the following week.
-
Signature Play: The Classic Cocktail Is Dead. Or Is It?
Classic cocktails are disappearing from India's cocktail menus. But they're still being ordered, taught to bartenders and borrowed from. So, who's really having the last drink?
-
A New Samvat Wishlist: Inclusive Prosperity And Human Development
India has strengthened its economic foundations through infrastructure, digital access and enterprise. Its next growth chapter must deepen productivity, create better livelihoods and widen participation in prosperity.
-
Love, Sex Aur Dhokha: The Audacious Plot To Spy On Jensen Huang
A Taipei dinner, a Singapore chip buyer and a suspected Chinese asset: inside the alleged spy operation that got close to NVIDIA's Jensen Huang.
-
Ten Things I Learnt This Samvat
Patience can be a trap. Cheap stocks can stay cheap. Leverage can wipe you out. What did Samvat 2082 teach us? Niraj Shah writes on 10 lessons from the year gone by.
-
Talking Points This Week: Tech Nerves, FII Buying, And A Faraway Banking Shock
The global markets are not shining this Diwali. The exception in the large markets is, India.
-
Midterm Rally Lasted A Day. The Hard Reality Of A Divided US May Last Two Years | Opinion
Between a contested AI boom, a debt ceiling that arrives in 2027 and a president with every incentive to act alone, the next two years may prove more volatile than the first day's rally suggests.
-
Blue Wave Will Derail the AI Trade but Won't Dismantle the AI Era | Unhedged Position
The Democrats' sweep of the US Congress will see politics collide with economic forces both over the long and short term.
-
It's Time To Take The GST Council's Bet On Trust Global
Payment records can prove India's services exports, and clear, proportionate rules can bring foreign digital sellers into the tax net.









