The five brokerage reports point to a common investment argument: HDFC Bank's loan growth is recovering, asset quality remains stable and margins may improve from the third quarter of FY27. At the same time, the reports show that the lender faces challenges in rebuilding its earlier competitive advantage. Nirmal Bang has maintained its Buy rating with a target price of Rs 1,000, implying 37% upside, while Anand Rathi has retained Buy with a target price of Rs 966, suggesting approximately 33% upside.
NDTV Profit's special research section collates quality and in-depth equity and economy research reports from across India's top brokerages, asset managers and research agencies. These reports offer NDTV Profit's subscribers an opportunity to expand their understanding of companies, sectors and the economy.
Nirmal Bang, ICICI Securities, Anand Rathi, IDBI Capital, Systematix
HDFC Bank Ltd.'s second-quarter FY27 results have prompted five brokerages to retain their Buy recommendations on the country's largest private-sector lender, even as margin pressure, deposit costs and the pace of post-merger recovery remain key concerns.
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
Nirmal Bang has maintained its Buy rating with a target price of Rs 1,000, implying 37% upside, while Anand Rathi has retained Buy with a target price of Rs 966, suggesting approximately 33% upside.
IDBI Capital has maintained Buy with a target price of Rs 950, indicating 30% upside.
ICICI Securities has retained its Buy rating and unchanged target price of Rs 920, implying 26% upside, while Systematix has maintained Buy with an unchanged target price of Rs 875, indicating approximately 20% upside.
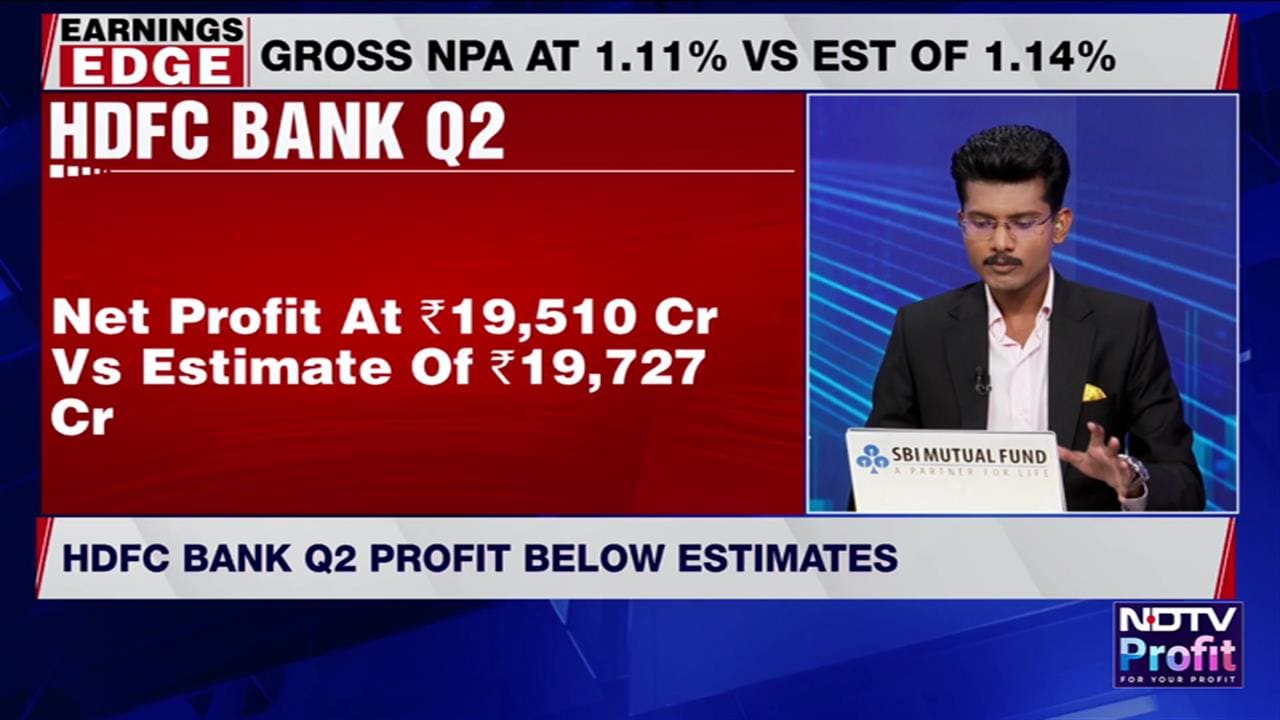
The recommendations follow a quarter in which HDFC Bank reported a 4.7% YoY rise in standalone net profit to Rs 19,510 crore, compared with Rs 18,641 crore in the corresponding period last year. Profit increased 2.4% sequentially.
The lender's net interest income rose 9.7% YoY to Rs 34,619 crore, while operating profit increased 5.6% to Rs 29,483 crore. Total deposits grew 18.8% to approximately Rs 33.27 lakh crore, and advances increased 16.4% to nearly Rs 31.96 lakh crore.
ALSO READ | Axis Bank Q2 Review: ICICI Securities Sees Up To 26% Upside; Check Other Brokerages Target Prices, Ratings
However, the net interest margin on interest-earning assets declined eight basis points sequentially to 3.32%, reflecting the impact of foreign currency non-resident, or FCNR(B), deposits and a higher share of term deposits. The bank's gross non-performing asset ratio improved to 1.11% from 1.17% in the previous quarter, while the net NPA ratio stood at approximately 0.37%.
The broad consensus across brokerage reports is that HDFC Bank's margins may have reached their lowest point in Q2 FY27, with a recovery possible from the December quarter. However, analysts remain divided over the speed at which the bank can regain its earlier advantage in loan growth, funding costs and profitability.
Click on the attachment to read the full report:
DISCLAIMER
This report is authored by an external party. NDTV Profit does not vouch for the accuracy of its contents nor is responsible for them in any way. The contents of this section do not constitute investment advice. For that you must always consult an expert based on your individual needs. The views expressed in the report are that of the author entity and do not represent the views of NDTV Profit.
Users have no license to copy, modify, or distribute the content without permission of the Original Owner.
Essential Business Intelligence, Sharp Market Insights, Practical Personal Finance Advice, Daily Fuel, Gold and Silver Prices and Latest Stories — On NDTV Profit.