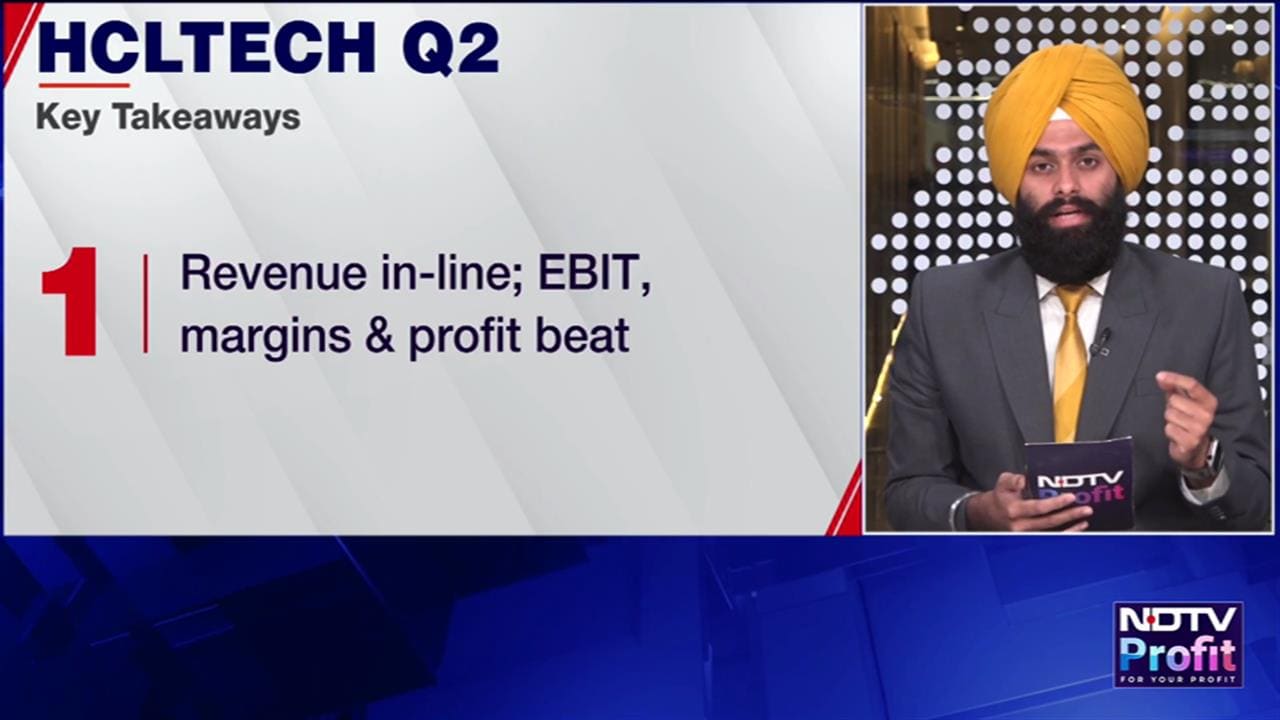
HCLTech's advanced AI revenue hit $219 million, up 78%YoY, carries higher margins, and is becoming a visible, genuine growth engine. Ebit margin expanded 131 bps to 18.2%, driven by Project Ascent, AI efficiencies and selling, general and administrative leverage, beating management expectations. Software revenue fell 5.8% on fewer multi-year renewals, but ARR grew 7.6%; the trimmed 4% guidance top-end looks conservative.
NDTV Profit's special research section collates quality and in-depth equity and economy research reports from across India's top brokerages, asset managers and research agencies. These reports offer NDTV Profit's subscribers an opportunity to expand their understanding of companies, sectors and the economy.
IDBI Capital Report
IDBI Capital maintained Hold rating on HCLTech Ltd. with an unchanged Rs 1,380 target price, implying about 13% potential upside from the report's currebt market price of Rs 1,220.
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
The brokerage highlighted Advanced AI revenue growth of 78% YoY to $219 million, a 131-bps QoQ expansion in Ebit margin to 18.2%, and $3.3 billion of bookings, while calling FY27 guidance conservative.
The brokerage highlighted that HCLTech delivered one of its cleanest quarters in a while. Revenue of $3,724 million grew 2.3% QoQ and 2.6% YoY in constant currency, with services up 3% QoQ and 4% YoY (2.3% organic).
Inorganic contribution was about $35.6 million, mostly from the HPE Telco Solutions deal (two months) and Jaspersoft. Growth was broadbased: five of seven verticals grew YoY, led by retail and consumer packaged goods (+14%) and financial services (+7.1%), while the US grew 3.5% and India 21.8%, though Europe slipped 0.3%.
ALSO READ | HCLTech Share Price Jumps 5% After Q2 Beat; Brokerages Split On Growth Outlook
Bookings of $3.3 billion, up 35% QoQ and 27% YoY, were the second-highest ever and the strongest first half on record. The real story is earnings quality.
Advanced AI revenue reached $219 mn, up 78% YoY, and now runs at $876 mn annualised, with management guiding to services margins 7-10% above traditional work and 70%+ gross margins on IP and platforms.
Click on the attachment to read the full report:
DISCLAIMER
This report is authored by an external party. NDTV Profit does not vouch for the accuracy of its contents nor is responsible for them in any way. The contents of this section do not constitute investment advice. For that you must always consult an expert based on your individual needs. The views expressed in the report are that of the author entity and do not represent the views of NDTV Profit.
Users have no license to copy, modify, or distribute the content without permission of the Original Owner.
Essential Business Intelligence, Sharp Market Insights, Practical Personal Finance Advice, Daily Fuel, Gold and Silver Prices and Latest Stories — On NDTV Profit.