Gland Pharma, Laurus Labs Shares Gain On Jefferies' 'Buy' Rating
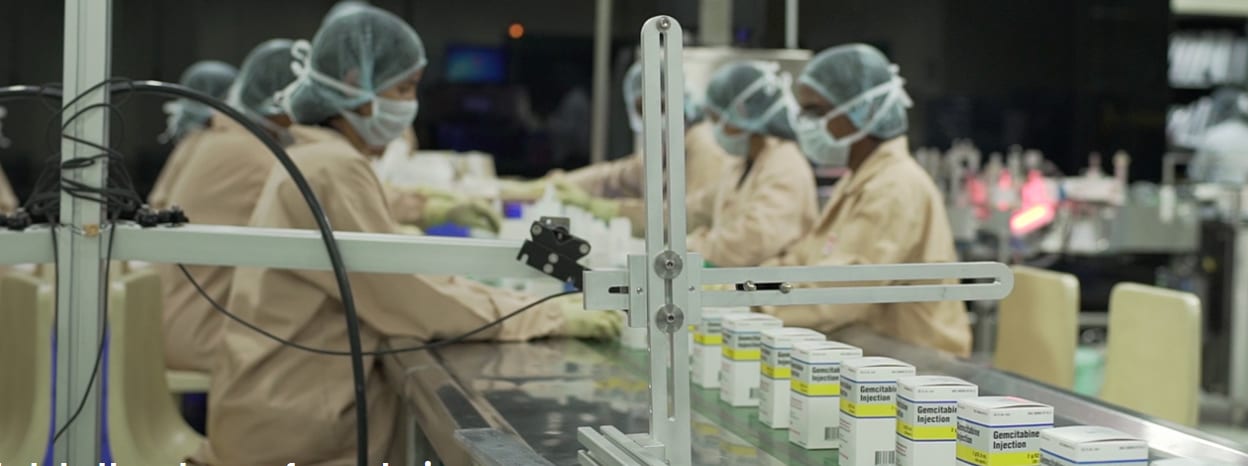
Shares of Gland Pharma Ltd. and Laurus Labs Ltd. rose after Jefferies initiated coverage on the drugmakers with a 'buy'.
Dominance in generic injectables, less exposure to pricing risk and ability to increase biosimilar capacity augur well for Gland Pharma, the research house said in a note. Investments in active pharmaceutical ingredients, finished dosage and custom synthesis, and acquisition of biotech firm Richcore Lifesciences' are growth triggers for Laurus Labs, it said.
Jefferies has set a price target of Rs 4,556 apiece, implying a potential upside of 17.51%, on Gland Pharma. For Laurus Labs, it is Rs 628, implying a potential upside of 20.99%.

Jefferies On Gland Pharma
Initiates coverage with a 'buy', with a price target at Rs 4,556—an implied return of 17.51%.
Gland Pharma's dominance in generic injectables, track record on the U.S. FDA audits, and less exposure to pricing risk augur well.
The company will benefit from economies of scale due to specialisation in injectables.
The company does not face the pricing pressure that other Indian generic firms face and has capabilities to pass on cost pressure, if it emerges.
It has adequate capacity to venture into new markets.
With 1,501 products registered across 60 countries, volume growth and new product launches will aid growth in the U.S. and rest of the world.
The company has pending abbreviated new drug applications and tentative approvals for products worth $7.5 billion.
It can leverage its relationship with promoter, Fosun Pharma, to penetrate into Latin American markets like Mexico.
The company's strategy to increase biosimilar capacity from 10 kl to 60 kl could be a key trigger for growth.
Its growth prospects remain strong with healthy pipeline of products in the U.S.
Values Gland Pharma at 36.5 times FY24E earnings per share; top pick in the sector.
Shares of Gland Pharma rose as much as 2.71%, the biggest intraday gain in over a week, to Rs 3,991 apiece before closing with gains of 1.45%. Of the 17 analysts tracking the company, 13 maintain a 'buy' and two each recommend a 'hold' and a 'sell', according to Bloomberg data. The overall consensus 12-month price target implies an upside of 5.1%.
Jefferies on Laurus Labs
Initiates coverage with a 'buy' and a price target of Rs 628 apiece—an implied return of 20.99%.
Laurus Labs' diversification strategy and investments in API, finished dosage and custom synthesis to drive growth.
Recent acquisition of Richcore is likely to provide the company a launching pad in recombinant animal-free food proteins.
Efforts to ensure self-sufficiency to the custom synthesis business are a major positive.
The company has attained a lion's market share in antiretroviral APIs. API business will now be driven by non-oncology and non-antiretroviral APIs.
Expects API business to grow 8% during FY21-FY24.
Custom synthesis will be a valuation driver with the company's recent tie-up with a European life science player for the supply of niche APIs to drive growth.
Expects Laurus Labs to maintain its leadership position in the market.
The company has initiated a large capex cycle that is expected to double its gross block—total value of assets a company owns.
Builds in 17%/17%/18% revenue/Ebitda/earning per share growth over FY21-24.
Values Laurus Labs at 21.5 times FY24E earnings per share.
Shares of Laurus Labs rose as much as 5%, the biggest intraday gain in over five weeks, to Rs 546 apiece, before ending the session with gains of 1.58%. Of the 13 analysts tracking the company, nine maintain a 'buy' and four suggest a 'sell'. The overall consensus 12-month price target implies an upside of 13%.

-
India's Troika Of Good Luck | Joining The Dots

A weaker Trump, a cooling AI trade and resilient earnings have put Indian markets back in favour. Rising inflation could spoil the party.
-
Talking Points This Week: Leadership Shock At Nvidia, Earnings Strength, And The Fog Over Hormuz
The Anthropic IPO pricing and first trading day, Nvidia's upcoming earnings, and any fresh signals from Iran will set the tone for the following week.
-
Signature Play: The Classic Cocktail Is Dead. Or Is It?
Classic cocktails are disappearing from India's cocktail menus. But they're still being ordered, taught to bartenders and borrowed from. So, who's really having the last drink?
-
A New Samvat Wishlist: Inclusive Prosperity And Human Development
India has strengthened its economic foundations through infrastructure, digital access and enterprise. Its next growth chapter must deepen productivity, create better livelihoods and widen participation in prosperity.
-
Love, Sex Aur Dhokha: The Audacious Plot To Spy On Jensen Huang
A Taipei dinner, a Singapore chip buyer and a suspected Chinese asset: inside the alleged spy operation that got close to NVIDIA's Jensen Huang.
-
Ten Things I Learnt This Samvat
Patience can be a trap. Cheap stocks can stay cheap. Leverage can wipe you out. What did Samvat 2082 teach us? Niraj Shah writes on 10 lessons from the year gone by.
-
Talking Points This Week: Tech Nerves, FII Buying, And A Faraway Banking Shock
The global markets are not shining this Diwali. The exception in the large markets is, India.
-
Midterm Rally Lasted A Day. The Hard Reality Of A Divided US May Last Two Years | Opinion
Between a contested AI boom, a debt ceiling that arrives in 2027 and a president with every incentive to act alone, the next two years may prove more volatile than the first day's rally suggests.
-
Blue Wave Will Derail the AI Trade but Won't Dismantle the AI Era | Unhedged Position
The Democrats' sweep of the US Congress will see politics collide with economic forces both over the long and short term.
-
It's Time To Take The GST Council's Bet On Trust Global
Payment records can prove India's services exports, and clear, proportionate rules can bring foreign digital sellers into the tax net.









