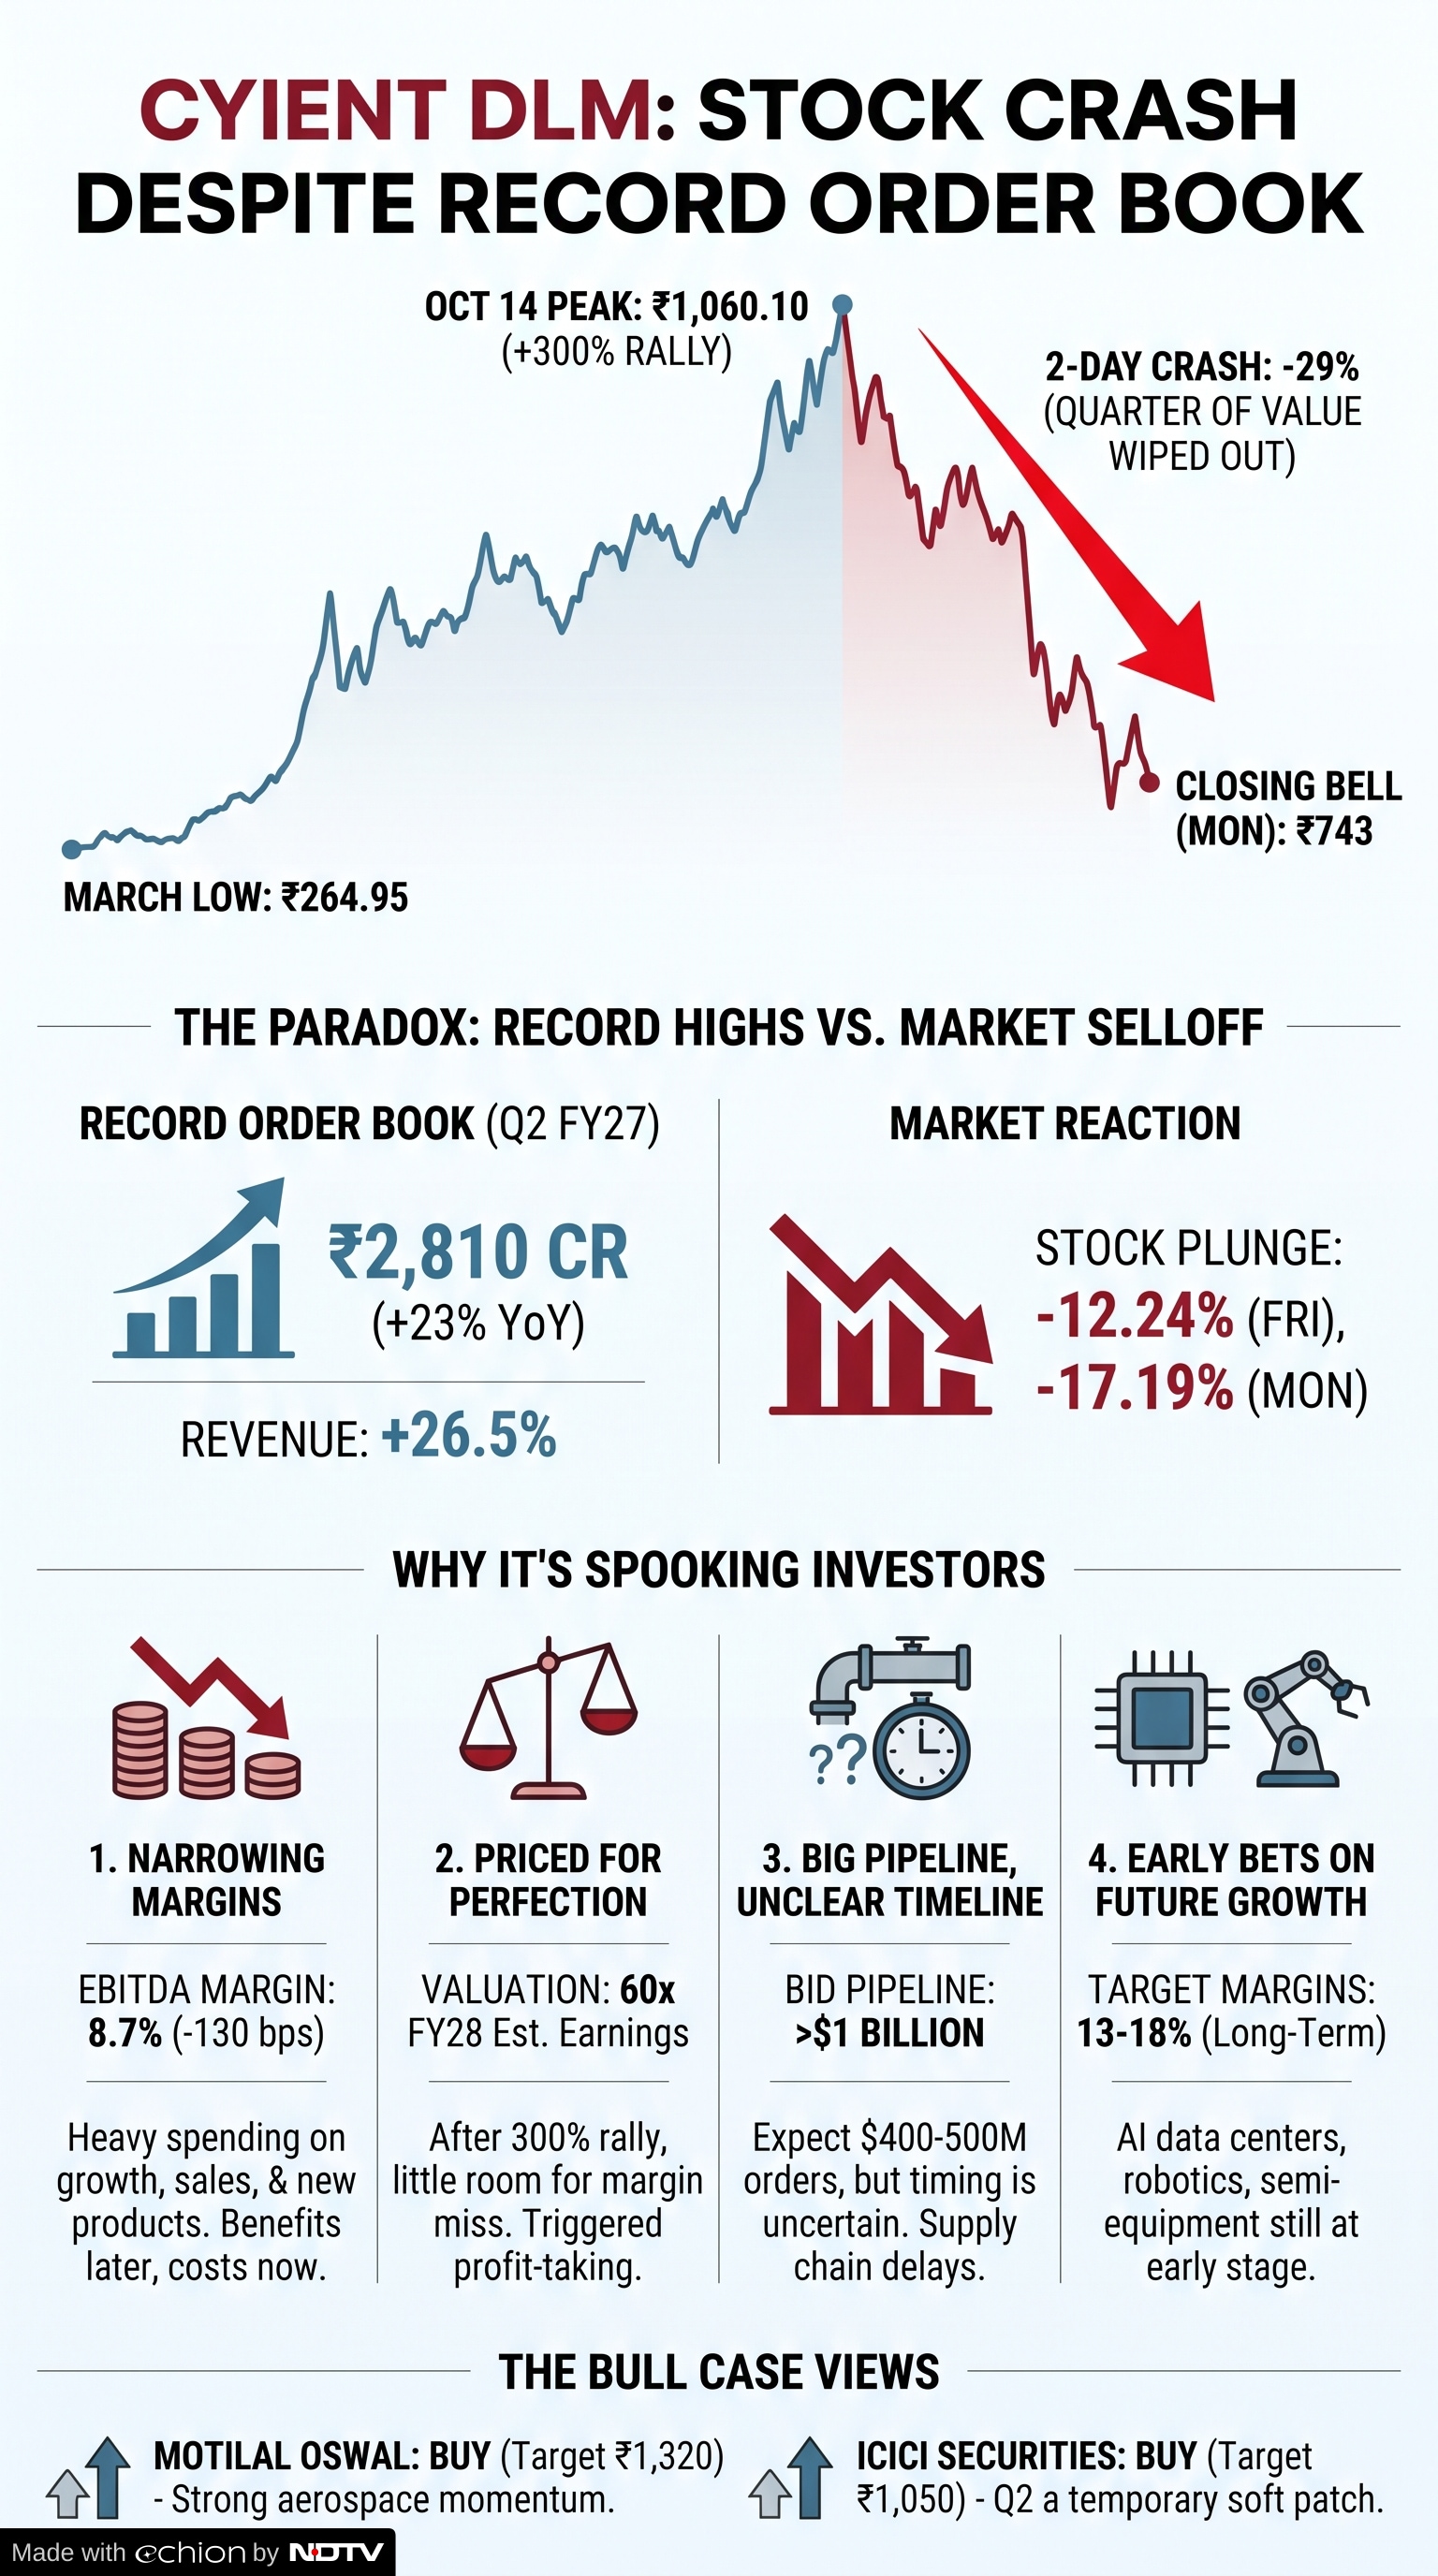
- Cyient DLM stock fell nearly 29% in two days despite record high order book
- Q2 revenue grew 26.5%, but EBITDA margin dropped 130 basis points to 8.7%
- Stock surged 300% since March, now valued at 60 times estimated FY28 earnings
The selloff in Cyient DLM's stock shows no signs of easening, with the stock being hammered for two consecutive days at the Dalal Street. About a quarter of the scrip value has been wiped out in less than two trading sessions, and the crash came despite the fact that the company's order book has hit a record high.
Cyient DLM order book surged to an all-time high of Rs 2,810 crore in the September quarter, up 23% year-on-year, and revenue grew 26.5%. Yet, the scrip follows a different trajectory post the Q2 results. The stock fell 12.24% on Friday, followed by a 17.19% plunge on Monday. The shares were valued at Rs 743 apiece at closing bell on the NSE, down nearly 29% from its closing price of Rs 1,038.9 on Thursday.
Here's a look at what is spooking investors.
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
1. Growth is getting more expensive
What has emerged as the biggest concern for investors is the narrowing margins. Even as the topline has grown, Cyient DLM's Ebitda margin fell 130 basis points to 8.7% in Q2FY27. This comes at a time when the company is spending heavily on growth. It has expanded its sales and bidding teams, appointed a Chief Growth Officer and kept spending on new product development.
Management says margins will improve as revenue grows, guiding for 9-10% Ebitda margin in FY27 and over 11% in FY28. For now, though, investors are paying for costs that are already here, while the benefits will come later.
2. Priced for perfection after a 300% rally
The stock was priced for strong growth going into the results. It had risen about 300% from its 52-week low of Rs 264.95 in March, and hit a record Rs 1,060.10 on Oct. 14, the day before results. At that level, there was little room for a miss, and the margin disappointment set off heavy profit-taking. The stock is now about 28% below that peak, but valuations remain rich. ICICI Securities' Rs 1,050 target values the stock at 60 times its estimated FY28 earnings.
ALSO READ: Investors Lose Rs 4.67 Lakh Crore As Sensex Tumbles Over 1,000 Points, Nifty Sheds 1.3%
3. A big pipeline, but no clear timeline
Management expects $400-500 million in new orders from a bid pipeline of more than $1 billion, but it is not clear when those orders will come in. Longer supply chain lead times also slowed deliveries during the quarter. In a business where revenue depends on delivering orders, that uncertainty matters.
4. New growth areas are still early
Cyient DLM is betting on AI data centres, robotics and semiconductor equipment for its next leg of growth, and is targeting long-term margins of 13-18%, up from 9-11% now. These businesses are still at an early stage, so investors will have to wait to see the results.
The bull case
The record order book is why not everyone is selling. Motilal Oswal has a ‘Buy' rating with a target of Rs 1,320, saying it still sees strong growth ahead, helped by continued aerospace momentum and a rising share of box-build revenue. ICICI Securities also has a ‘Buy', with a target of Rs 1,050, and calls Q2 a temporary soft patch. PL Capital is more cautious, with a ‘Reduce' rating and a target of Rs 873.
From hereon, a solid recovery in Cyient DLM's stock would depend on its performance in the ongoing quarter. A conversion of stronger order into better margins could be compelling enough for the investors to return.
ALSO READ: PNB Grows Profit Slower Than ICICI Bank And Axis, Yet Its Stock Outran Them. Four Reasons Why
Essential Business Intelligence, Sharp Market Insights, Practical Personal Finance Advice, Daily Fuel, Gold and Silver Prices and Latest Stories — On NDTV Profit.