Analysts Cut Lupin’s Target Price After Surprise Loss In Q2
Most analysts cut target price for Lupin Ltd. after the nation's third-largest drugmaker reported a surprise loss in the quarter ended September.
Net loss stood at Rs 127 crore compared with a profit of Rs 266 crore a year ago, according to an exchange filing. That was on account of a one-time loss of Rs 546 core due to adjustments made during the quarter, including provisions worth Rs 379 crore toward a Texas lawsuit and a loss of Rs 167 crore toward selling stake in a Japanese joint venture, Lupin said in the filing.
The company's operational performance, however, beat estimates aided by new chemical entity licensing income.
Still, analysts said that Lupin's margins remained weak on account of higher research and development, and personnel costs. Thus, they cut earnings per share estimates for the ongoing financial year. But Lupin is confident of achieving Ebitda margin of 18-20 percent in the rest of 2019-20.
The company, in a post-earnings conference call, also said its U.S. business has now stabilised and will grow on account of capacity expansion of Levothyroxine (used to treat an underactive thyroid gland) and the launch of injectables portfolio. Markets like India continue to deliver solid growth, it said.
Key highlights of Lupin's post-earnings concall
- Base business erosion is down to low single-digits in the U.S.
- Levothyroxine capacity expansion on schedule and should ramp up from the fourth quarter of FY20.
- Supply has stabilised and ramped up ahead of schedule for Levothyroxine.
- Will file response to Proair (used to treat or prevent bronchospasm) complete response letter next month, hope to launch in the first six months of FY21.
- Upside from cost reduction and efficiency initiatives reflecting to some extent.
- Expects U.S. FDA re-inspection of Goa and Somerset in fourth quarter; Pithampur and Mandideep can take one more quarter.
- Committed to keep R&D costs below 10 percent of sales in FY20.
- Management expects the tax rate for FY20 to be 45 percent.
- Management expects Ebitda margin at 18-20 percent range for the rest of FY20.
Here's what brokerages have to say about Lupin's Q2 Results 2019-20
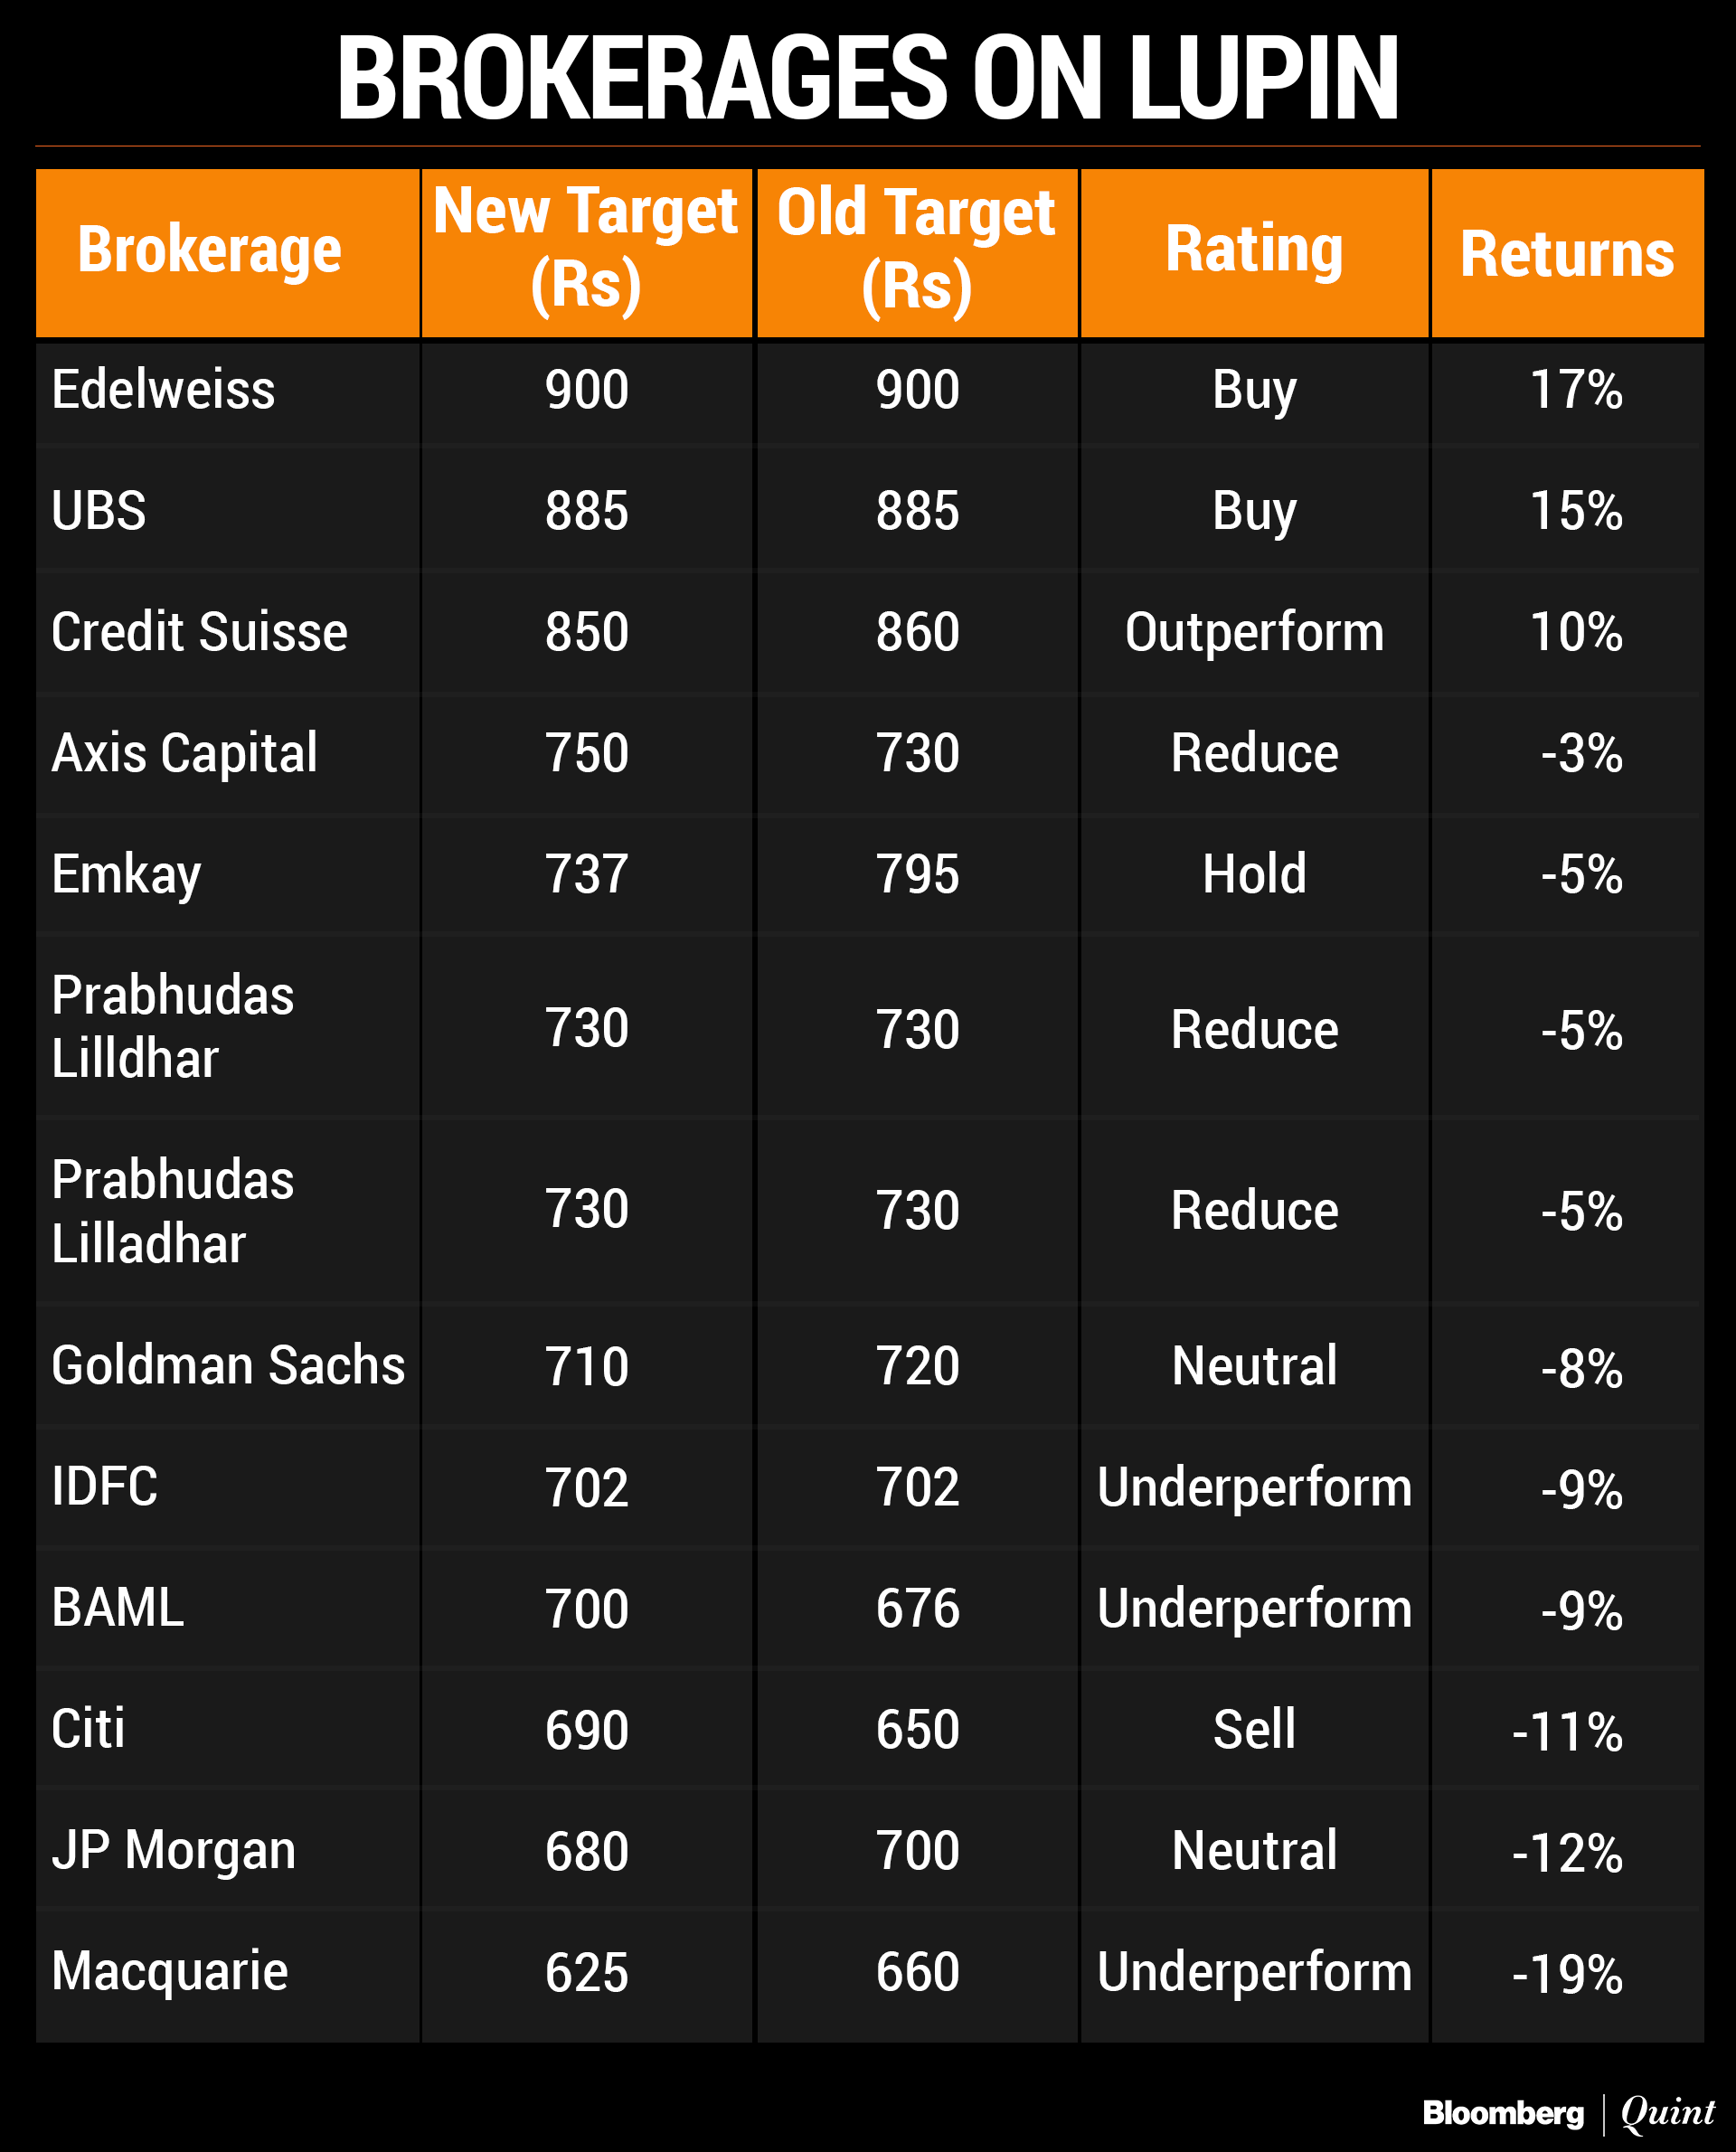
Citi
- Hikes target price to Rs 690 from Rs 650.
- Maintains sell on stock as it sees no meaningful recovery yet.
- Revenue growth remains sluggish, while margins remain under pressure.
- Cuts FY20-22 EPS estimate by 7-8 percent to reflect weaker-than-expected base business margins.
- Valuations remain rich.
Credit Suisse
- Maintains ‘Outperform' but cuts target price to Rs 850 from Rs 860 apiece.
- Ebitda margin was weak; declined due to higher R&D and personnel costs.
- Base business level of $184 million is higher than expected.
Edelweiss
- Maintains ‘Buy' with a target price of Rs 900 apiece.
- U.S. business struggled as company has been unable to ramp-up Solosec (used to treat vaginal infection).
- Expects prospects to improve significantly from FY21 onwards even as FY20 will be challenging.
- Reiterates that downside potential is limited at current valuation.
- Specialty, respiratory and biosimilar launches key for revival.
Goldman Sachs
- Maintains ‘Neutral' but cuts target price to Rs 710 from Rs 720 apiece.
- Cuts EPS estimates by 4-6 percent to incorporate slower commercialisation of key pipeline assets.
- Slow ramp in U.S. business drives soft margin as Ranexa (used to chronic treat angina or chest pain) exclusivity cycled.
Prabhudas Lilladher
- Maintains ‘Reduce' with a target price of Rs 730 apiece.
- Overheads and warning letter to remain overhang for valuation.
- Lack of control on overheads may percolate lesser benefits in earnings in the U.S.
- U.S. branded business remained tepid at $5 million sales in second quarter.
UBS
- Maintains ‘Buy' with a target price of Rs 885 apiece.
- Potential sale of Japan business could be materially EPS accretive.
- Higher R&D and personnel costs impact core operating margins.
- Potential boost to U.S. business from levothyroxine, while lingering regulatory concerns.

-
Foreign Investors Own Half Of HDFC Bank and ICICI Bank. An LTCG Cut Could Matter Most Here

Foreign portfolio investors have US$115 billion parked in HDFC Bank, ICICI Bank. If the government cuts long-term capital gains tax, Jefferies says returning foreign money could land here first.
-
'Never Seen This Level Of Negativity': Sandeep Tandon Says The Next Rally May Be Closer Than You Think
Veteran investor Sandeep Tandon says foreign selling is easing, large-caps are due a comeback and mid-caps are crowded, while he turns positive on gold, power and pharma this Diwali.
-
Indians Stay With Family, Not In Hotels | The Reason Why
India still lacks enough clean, reliable and affordable hotels for budget-conscious travellers.
-
The Economic Imperative: Analysing The Material Driving Force Behind India-Canada Strategic Reset
This economic complementarity is further reinforced by deep institutional investment ties and talent mobility, which form the bedrock of the bilateral framework.
-
Medicine Pricing: Where Must Profit Stop?
India must confront excessive margins, hidden incentives and regulatory gaps that threaten the integrity of medicine.
-
Why Amazon And Flipkart Are Struggling To Beat Meesho In India's Smaller Cities
With 274 million users and lowest-cost logistics, Meesho is defending its value commerce crown against giants like Amazon and Flipkart.
-
High US Salaries, No Green Card Certainty: The Financial Calculation Facing Indian H-1B Families
The suspension of PERM processing at eight technology employers does not cancel existing H-1B visas. What it does is force a question many Indian families have been avoiding: is the US salary worth tying your career and family plans to one employer?
-
Swiggy vs Eternal: Food Delivery's Two Rivals Are No Longer In The Same Race
Eternal is building a private AI assistant, dark.ai. Swiggy is still working out how to make Instamart pay, with an operating loss of Rs 895 crore in the July-September quarter while Blinkit stayed profitable.
-
Where You Live Shapes How You Get To Work | The Reason Why
Two-wheelers are the most popular way to get to work in India, accounting for nearly 43% of workplace commutes.
-
Unhedged Position: Can India See An Indonesia-Style Time Correction?
The Nifty is trading below levels it first clocked in 2024. Is there, then, as I have suggested in the headline, potential that the current time correction drags on painfully for the next three-five, even ten years?










