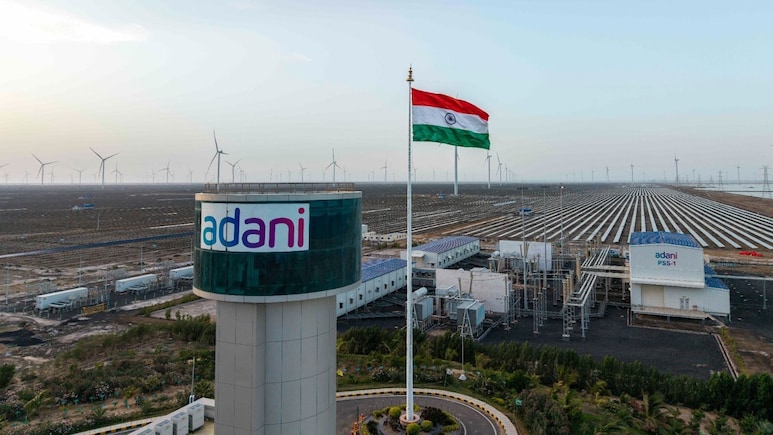
Adani Green has the strongest track record of developing a renewables portfolio, with the resources to develop up to 30GW at a single location in Khavda, highlights ICICI Securities. The company remains significantly ahead of the competition. Its capex-to-Ebitda ratio of ~7.5 times indicates high capital efficiency. But Adani has been impacted by declining grid availability, resulting in a loss of Ebitda. To offset this, it has accelerated BESS deployment whose impact has been captured in locked-in Ebitda (increased to Rs 28,000 crore from Rs 27,000 crore earlier.
NDTV Profit's special research section collates quality and in-depth equity and economy research reports from across India's top brokerages, asset managers and research agencies. These reports offer NDTV Profit's subscribers an opportunity to expand their understanding of companies, sectors and the economy.
ICICI Securities Report
Following Adani Green Energy Ltd.'s September-quarter results, the brokerage firm ICICI Securities has maintained Add rating with a revised target price of Rs 1,430 from Rs 1,650 earlier, and has valued the stock at 14 tiimes locked-in Ebitda.
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
The brokerage highlighted that Adani Green reported a good quarter with revenue growth of 40% YoY to Rs 4,140 crore. Its Ebitda grew 46% YoY to Rs 3,800 crore and PAT stood at Rs 660 crore, all ahead of consensus estimates.
Total generation for Q2 FY27 stood at 12 billion units (+33% YoY). Wind plant load factor improved 510 basis points YoY in H1 FY27 on the back of favourable wind conditions.
Outlook and Valuation
Adani Green has the strongest track record of developing a renewables portfolio, with the resources to develop up to 30GW at a single location in Khavda. The company remains significantly ahead of the competition. Its capex-to-Ebitda ratio of ~7.5 times indicates high capital efficiency.
But Adani has been impacted by declining grid availability, resulting in a loss of Ebitda.
To offset this, it has accelerated BESS deployment whose impact has been captured in locked-in Ebitda (increased to Rs 28,000 crore from Rs 27,000 crore earlier.
The brokerage expected the connectivity issue to be resolved by Dec'26 with the commissioning of a 7GW line. This is now delayed by at least a quarter and remains a key monitorable.
Further, delays could also possibly slow down its capacity addition. Considering these factors, ICICI Securities has trimmed its valuation multiple to 14 times vs 16x earlier.
Key risks:
Delay in commissioning of under-development capacity; and lower than-estimated generation, are the key risks to the brokerage's call.
Click on the attachment to read the full report:
DISCLAIMER
This report is authored by an external party. NDTV Profit does not vouch for the accuracy of its contents nor is responsible for them in any way. The contents of this section do not constitute investment advice. For that you must always consult an expert based on your individual needs. The views expressed in the report are that of the author entity and do not represent the views of NDTV Profit.
Users have no license to copy, modify, or distribute the content without permission of the Original Owner.
Essential Business Intelligence, Sharp Market Insights, Practical Personal Finance Advice, Daily Fuel, Gold and Silver Prices and Latest Stories — On NDTV Profit.