Opinion: Not Quite The "Fog A Mirror, Buy A House," But Crypto-Based Mortgages Are Crazy
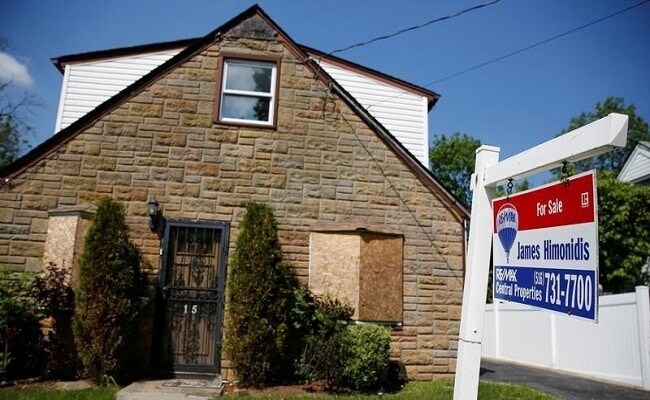
If you entered a contest to see who could design a financial instrument to lose the most money the fastest, you would struggle to come up with a better idea than taking home mortgages backed by crypto, slicing them into mortgage-backed securities and selling them at the moment the global financial system is being bludgeoned by pandemic, war and Jerome Powell.
And yet here we are: Bloomberg News reports the hot new thing in finance is the nouveau crypto riche putting up their expensive digital assets as collateral to buy expensive houses using a more-or-less traditional mortgage, but with no dead-tree dollars down.
The brainchild of a company called Milo Credit — based in America's Crypto Capital, Miami — this offering goes a little further than what we've seen so far, which has included the use of crypto for home down-payments and apartment deposits and the occasional crib selling as an NFT.
Naturally the world's MBS sausage-makers want in. “We see a lot of interest in this area and expect it will develop into a new asset class,” a Sidley Austin lawyer tells Bloomberg.
For sure! But each one of these things should be sold with a pair of asbestos gloves to handle them, given the layers of red-hot risk being piled on at every step.
First you've got the collateralization with crypto, a famously stable asset that rose 305% in 2020 and has plunged 40% lately. Using mortgage helps crypto owners avoid cashing out and paying taxes to raise dollars.
But the loan terms subject them to possible capital calls or even property seizure if the “crypto-to-loan amount” — a series of words if ever there was one — crosses certain thresholds.
Those thresholds seem pretty steep — a 65% drop in collateral value, for example.
But given how much crypto can swing in an hour or a day, it will be interesting to see how these terms are applied, and by “interesting” I mean “like being held at gunpoint in a convenience store.”
Then you've got housing, which is a more reliably stable asset class, until it isn't. It's on shaky ground now that the Fed and a panicky credit market are raising interest rates. And by now we all know the deal with mortgage-backed securities.
They are a fine and reliable product, aside from that one time when they weren't. We are once again finding esoteric new ways to stress-test them.
Milo's loan process takes only a few weeks and requires little of those tedious stacks of paperwork that traditional mortgage lenders make you sign. The company's CEO recently told Barron's you don't even need a FICO credit check.
This is not quite the “fog a mirror, buy a house” days of the pre-crisis housing bubble, given the existence of real crypto wealth. But what if that all turns into so much fog?
This could just be cowardly naysaying. Crypto may well keep going to the moon. Home prices may never truly swoon again like they did 15 years ago. How much would you like your pension fund to bet on it?
To contact the author of this story: Mark Gongloff at mgongloff1@bloomberg.net
(Except for the headline, this story has not been edited by NDTV staff and is published from a syndicated feed.)

-
AI Bias In Investing Cannot Be Eliminated, But It Can Be Governed

Framing is a particularly important example as identical financial information presented in terms of gains rather than losses can lead an LLM to reach a different assessment.
-
Joining The Dots | Dark Skies, Steady Diya: Why Hope Holds This Diwali
With war, a weak rupee and foreign outflows weighing on sentiment, policymakers at the NDTV World Summit and market veterans at NDTV Profit Ignite: Diwali Edition offered the same advice: stay invested and filter out the noise.
-
The Curious Case of Equitas Small Finance Bank And A CEO Who Quit For Stock
PN Vasudevan believes persistent investor concerns over a perceived conflict of interest had become a governance overhang on Equitas Small Finance Bank's stock, even as the lender improved profitability and asset quality.
-
Talking Points This Week: AI Cash Burn, A Tiger Comeback And An India That Still Finds Its Own Path
India is not immune to higher oil or tighter global liquidity, yet its earnings base is broader, its domestic policy levers are still available.
-
Foreign Investors Own Half Of HDFC Bank and ICICI Bank. An LTCG Cut Could Matter Most Here
Foreign portfolio investors have US$115 billion parked in HDFC Bank, ICICI Bank. If the government cuts long-term capital gains tax, Jefferies says returning foreign money could land here first.
-
'Never Seen This Level Of Negativity': Sandeep Tandon Says The Next Rally May Be Closer Than You Think
Veteran investor Sandeep Tandon says foreign selling is easing, large-caps are due a comeback and mid-caps are crowded, while he turns positive on gold, power and pharma this Diwali.
-
Indians Stay With Family, Not In Hotels | The Reason Why
India still lacks enough clean, reliable and affordable hotels for budget-conscious travellers.
-
The Economic Imperative: Analysing The Material Driving Force Behind India-Canada Strategic Reset
This economic complementarity is further reinforced by deep institutional investment ties and talent mobility, which form the bedrock of the bilateral framework.
-
Medicine Pricing: Where Must Profit Stop?
India must confront excessive margins, hidden incentives and regulatory gaps that threaten the integrity of medicine.
-
Why Amazon And Flipkart Are Struggling To Beat Meesho In India's Smaller Cities
With 274 million users and lowest-cost logistics, Meesho is defending its value commerce crown against giants like Amazon and Flipkart.










