Netflix Is Looking To Become 'Debtflix' Again To Fund Warner Bros Acquisition
Netflix, a company that built its business on junk bonds, is looking to borrow heavily again.
The streaming company once known as “Debtflix” before it started generating heavy cash flow is looking to add tens of billions of dollars of debt to finance its planned $72 billion acquisition of most of Warner Bros. Discovery Inc. But Netflix Inc. has a stronger balance sheet than it did before the pandemic, which will probably allow the company to boost the price it pays in any bidding war that emerges, while remaining investment grade.
“Netflix's credit profile really turned around,” said Stephen Flynn, an analyst covering telecom and media debt at Bloomberg Intelligence. “They've come a long way from high yield.”
The company's current agreed acquisition includes $59 billion of temporary debt financing from Wall Street banks. The entertainment giant plans to eventually replace that with as much as $25 billion of bonds, $20 billion of delayed-draw term loans, and a $5 billion revolving credit facility. Some will probably also be paid down with cash flow.
The company's debt load might swell even more now that Paramount Skydance Corp. launched a hostile takeover bid for all of Warner Bros. that values the company at more than $108 billion including debt, around $26 billion more than Netflix's offer.
To a team of Morgan Stanley analysts led by David Hamburger, rising debt levels are a risk for Netflix investors now. The streaming company, graded A by S&P Global Ratings and a notch lower by Moody's Ratings at A3, is vulnerable to a cut to the BBB tier, the analysts wrote in a Monday note. They recommend selling the company's notes due in 2034 and 2054 given the potential for Netflix to issue significant amounts of new debt and see its ratings cut.
There are other risks for the company beyond downgrades: it must execute one of the largest media deals of all time. Regulators could move to block the transaction. And Paramount's hostile takeover bid may win over Netflix, in which case Netflix would be stuck paying a $5.8 billion penalty in the form of a breakup fee, without gaining a new business that would boost its revenue.
Still, many analysts and investors see the risks as manageable. Risk premiums on the company's debt are little changed over the last week. On Monday, Moody's affirmed Netflix's A3 rating, citing the company's strong operating performance and benefits it will gain from acquiring “some of the most highly regarded intellectual property in the media industry,” including Harry Potter, HBO and DC Comics. The ratings agency changed its outlook on the company to “stable” from “positive,” reflecting a slight increase in risk for the company from the acquisition.
According to Bloomberg Intelligence calculations, Netflix would have about $75 billion in debt if the acquisition goes through based on the latest terms, up from about $15 billion now. But even with much higher debt, the new company is expected next year to generate around $20.4 billion of earnings available to pay interest, known as earnings before interest, taxes, depreciation and amortization.
At that level, net debt would equal about 3.7 times Ebitda. Then in 2027, earnings would probably grow and bring the leverage ratio down to about mid-2x range, according to BI, a more typical level for an investment-grade company.
“Overall, Netflix is a very, very strong credit,” BI's Flynn said. “They've got growing revenue, growing Ebitda, and growing free cash flow, so the pro-forma company can de-lever quite quickly.”
Netflix's swelling debt load recalls the company's heavy borrowing before the pandemic, with a key difference: the streaming giant is much stronger now. Netflix first started selling junk bonds in 2009 when it was transitioning from mainly renting DVDs through the mail into a streaming company. Over the following years its debt load climbed to as high as $18.5 billion as it gained more rights to stream movies and television programs, and started producing hits like “House of Cards” and “Stranger Things.”
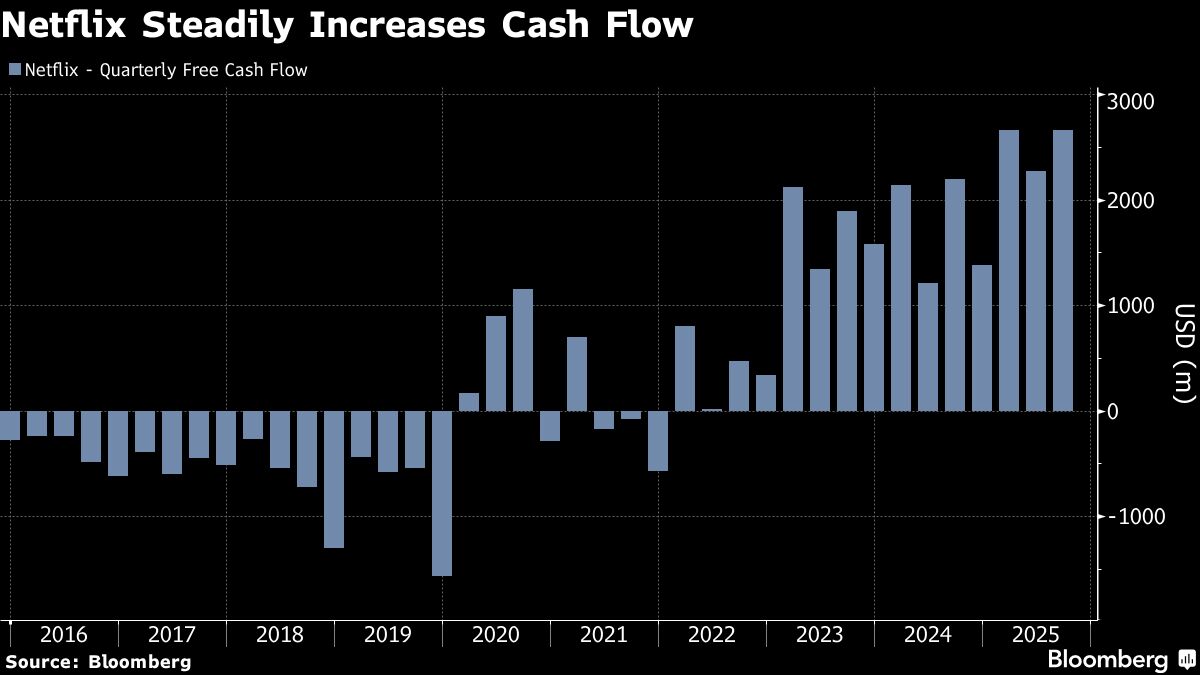
Some detractors called the company “Debtflix” as it piled on the liabilities. But then its investments came to look prescient. The global pandemic hit in 2020, and vast amounts of cash flowed into its coffers as people worldwide found themselves homebound in lockdown, desperate for entertainment. Netflix had a backlog of series and movies to release that proved even more valuable than the company had expected.
In 2023, the company started generating more than $6.9 billion of free cash flow every year. Bond raters upgraded it to investment grade status, allowing it to finance itself at a cheaper cost at a time when it needed less debt funding.
“Netflix has earned the right to take on an acquisition of this size,” said Jim Fitzpatrick, head of US investment-grade credit research at Allspring Global. “Their balance sheet has plenty of capacity to accommodate something like this, even if they have to up their bid.”

-
Getting To Work Costs Women More | The Reason Why

It is not just about women paying more than men. It is about women paying much more in cities than in villages.
-
AI Bias In Investing Cannot Be Eliminated, But It Can Be Governed
Framing is a particularly important example as identical financial information presented in terms of gains rather than losses can lead an LLM to reach a different assessment.
-
Joining The Dots | Dark Skies, Steady Diya: Why Hope Holds This Diwali
With war, a weak rupee and foreign outflows weighing on sentiment, policymakers at the NDTV World Summit and market veterans at NDTV Profit Ignite: Diwali Edition offered the same advice: stay invested and filter out the noise.
-
The Curious Case of Equitas Small Finance Bank And A CEO Who Quit For Stock
PN Vasudevan believes persistent investor concerns over a perceived conflict of interest had become a governance overhang on Equitas Small Finance Bank's stock, even as the lender improved profitability and asset quality.
-
Talking Points This Week: AI Cash Burn, A Tiger Comeback And An India That Still Finds Its Own Path
India is not immune to higher oil or tighter global liquidity, yet its earnings base is broader, its domestic policy levers are still available.
-
Foreign Investors Own Half Of HDFC Bank and ICICI Bank. An LTCG Cut Could Matter Most Here
Foreign portfolio investors have US$115 billion parked in HDFC Bank, ICICI Bank. If the government cuts long-term capital gains tax, Jefferies says returning foreign money could land here first.
-
'Never Seen This Level Of Negativity': Sandeep Tandon Says The Next Rally May Be Closer Than You Think
Veteran investor Sandeep Tandon says foreign selling is easing, large-caps are due a comeback and mid-caps are crowded, while he turns positive on gold, power and pharma this Diwali.
-
Indians Stay With Family, Not In Hotels | The Reason Why
India still lacks enough clean, reliable and affordable hotels for budget-conscious travellers.
-
The Economic Imperative: Analysing The Material Driving Force Behind India-Canada Strategic Reset
This economic complementarity is further reinforced by deep institutional investment ties and talent mobility, which form the bedrock of the bilateral framework.
-
Medicine Pricing: Where Must Profit Stop?
India must confront excessive margins, hidden incentives and regulatory gaps that threaten the integrity of medicine.










