Delhivery Gets ‘Buy’ Rating On Improved Margins, Volume Growth
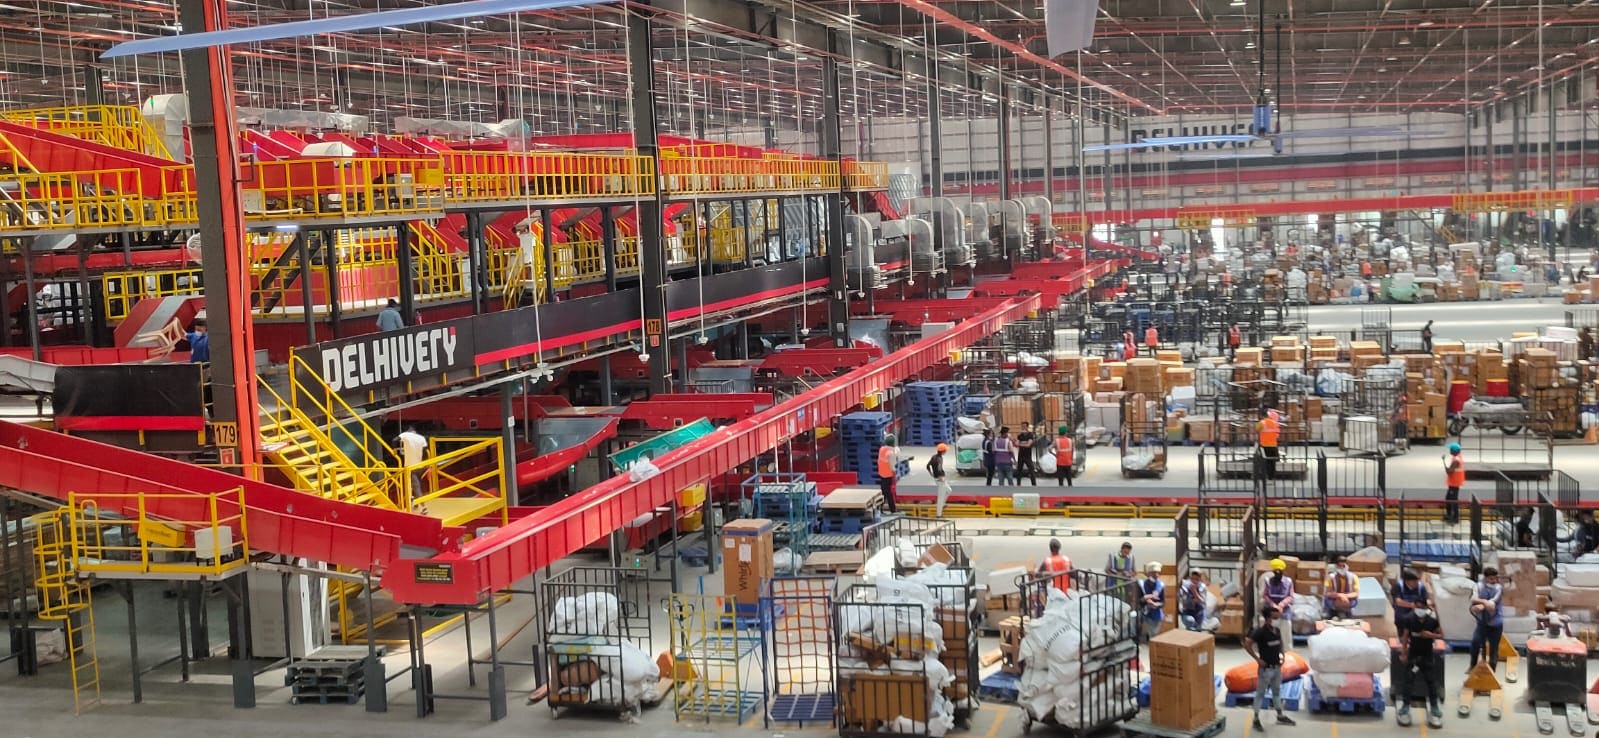
Delhivery Ltd. got a 'buy' rating from brokerages on improved margins, volume growth, and cost optimisation measures.
"The company has broken even at an adjusted Ebitda margin level. Positive momentum in margins was visible starting quarter 2, continued into quarter 3, and the same forces have continued into quarter 4 as well. The improvement in margins has been driven by increased utilisation across the network, with increased volumes and a number of cost optimisation measures," said Sahil Barua, management director and chief executive officer of Delhivery, during the fourth quarter earnings conference call.
Out of the 21 analysts tracking the company, 14 maintain a ‘buy' rating, five recommend a ‘hold,' and two recommend ‘sell,' according to Bloomberg data. The average 12-month consensus price target implies an upside of 17.9%.
The relative strength index is 46.19, implying that the stock is neither overbought, nor oversold.
Here is what brokerages have to say
Kotak Institutional Equities
Maintains a ‘buy' rating with a target price of Rs 410.
Delhivery's Tauru plant clears inventory 10 times a day versus 1x for its peers.
Due to the company's mesh network, 70% of the shipments go through direct routes, while this percentage is much lower for a hub-and-spoke player.
There is EPS growth to be observed moving forward.
The improvement in margin over FY2022-26E is expected to be 600 basis points.
The revenue CAGR over FY2023-26E is expected to be 22%.
Jefferies
The brokerage maintains a ‘buy' rating with a target price of Rs 570.
60% of the clients are large corporates and the balance are MSMEs, which helps with the margin profile.
3.2x FY2025E implied EV/Sales multiple
Delhivery is already dominant in B2C, and the company is now making a mark in B2B through its acquisition of Spoton.
The company should break even in FY2025-26E, with management's focus on profitability in an industry with a strong growth tailwind.
The e-commerce demand being higher than anticipated might lead to an upside scenario.
Continuing volume loss in Spoton might lead to a downside scenario.
Investec Capital Services (India) Pvt.
The brokerage rated the stock a ‘buy,' with a target price of Rs 415, implying an upside return potential of 15.90%.
Delhivery's mesh network allows it to reduce delivery time, improve productivity, and offer flexibility in terms of the route taken to deliver a parcel.
Management aims to achieve 20% service Ebitda and 14% Ebitda margins once the business achieves 3x its current scale.
Capex intensity is expected to settle at 5–6% of the revenue over the next few years.
Delhivery delivers approximately 2x parcels versus its closed peer.
Delhivery's market share has increased from 15% a few years ago to 22% now.

-
Getting To Work Costs Women More | The Reason Why

It is not just about women paying more than men. It is about women paying much more in cities than in villages.
-
AI Bias In Investing Cannot Be Eliminated, But It Can Be Governed
Framing is a particularly important example as identical financial information presented in terms of gains rather than losses can lead an LLM to reach a different assessment.
-
Joining The Dots | Dark Skies, Steady Diya: Why Hope Holds This Diwali
With war, a weak rupee and foreign outflows weighing on sentiment, policymakers at the NDTV World Summit and market veterans at NDTV Profit Ignite: Diwali Edition offered the same advice: stay invested and filter out the noise.
-
The Curious Case of Equitas Small Finance Bank And A CEO Who Quit For Stock
PN Vasudevan believes persistent investor concerns over a perceived conflict of interest had become a governance overhang on Equitas Small Finance Bank's stock, even as the lender improved profitability and asset quality.
-
Talking Points This Week: AI Cash Burn, A Tiger Comeback And An India That Still Finds Its Own Path
India is not immune to higher oil or tighter global liquidity, yet its earnings base is broader, its domestic policy levers are still available.
-
Foreign Investors Own Half Of HDFC Bank and ICICI Bank. An LTCG Cut Could Matter Most Here
Foreign portfolio investors have US$115 billion parked in HDFC Bank, ICICI Bank. If the government cuts long-term capital gains tax, Jefferies says returning foreign money could land here first.
-
'Never Seen This Level Of Negativity': Sandeep Tandon Says The Next Rally May Be Closer Than You Think
Veteran investor Sandeep Tandon says foreign selling is easing, large-caps are due a comeback and mid-caps are crowded, while he turns positive on gold, power and pharma this Diwali.
-
Indians Stay With Family, Not In Hotels | The Reason Why
India still lacks enough clean, reliable and affordable hotels for budget-conscious travellers.
-
The Economic Imperative: Analysing The Material Driving Force Behind India-Canada Strategic Reset
This economic complementarity is further reinforced by deep institutional investment ties and talent mobility, which form the bedrock of the bilateral framework.
-
Medicine Pricing: Where Must Profit Stop?
India must confront excessive margins, hidden incentives and regulatory gaps that threaten the integrity of medicine.










