Credit Card Usage In Smaller Towns Adding To Growth, Says SBI Cards’ Hardayal Prasad
WATCH | SBI Cards CEO Hardayal Prasad On How To Value The Company
Indians are spending more through their credit cards with time. This is true not just for large metropolitan cities but also for smaller towns. That is the demographic where SBI Cards and Payment Services sees significant potential for growth, said the company's Chief Executive Officer Hardayal Prasad in an interview with BloombergQuint.
A report from the Bank of International Settlements report said that there were two cards per every 100 consumers in India in 2017. This rose to three in 2018. The post-demonetisation period has led to a surge in digital payment adoption for day-to-day transactions.
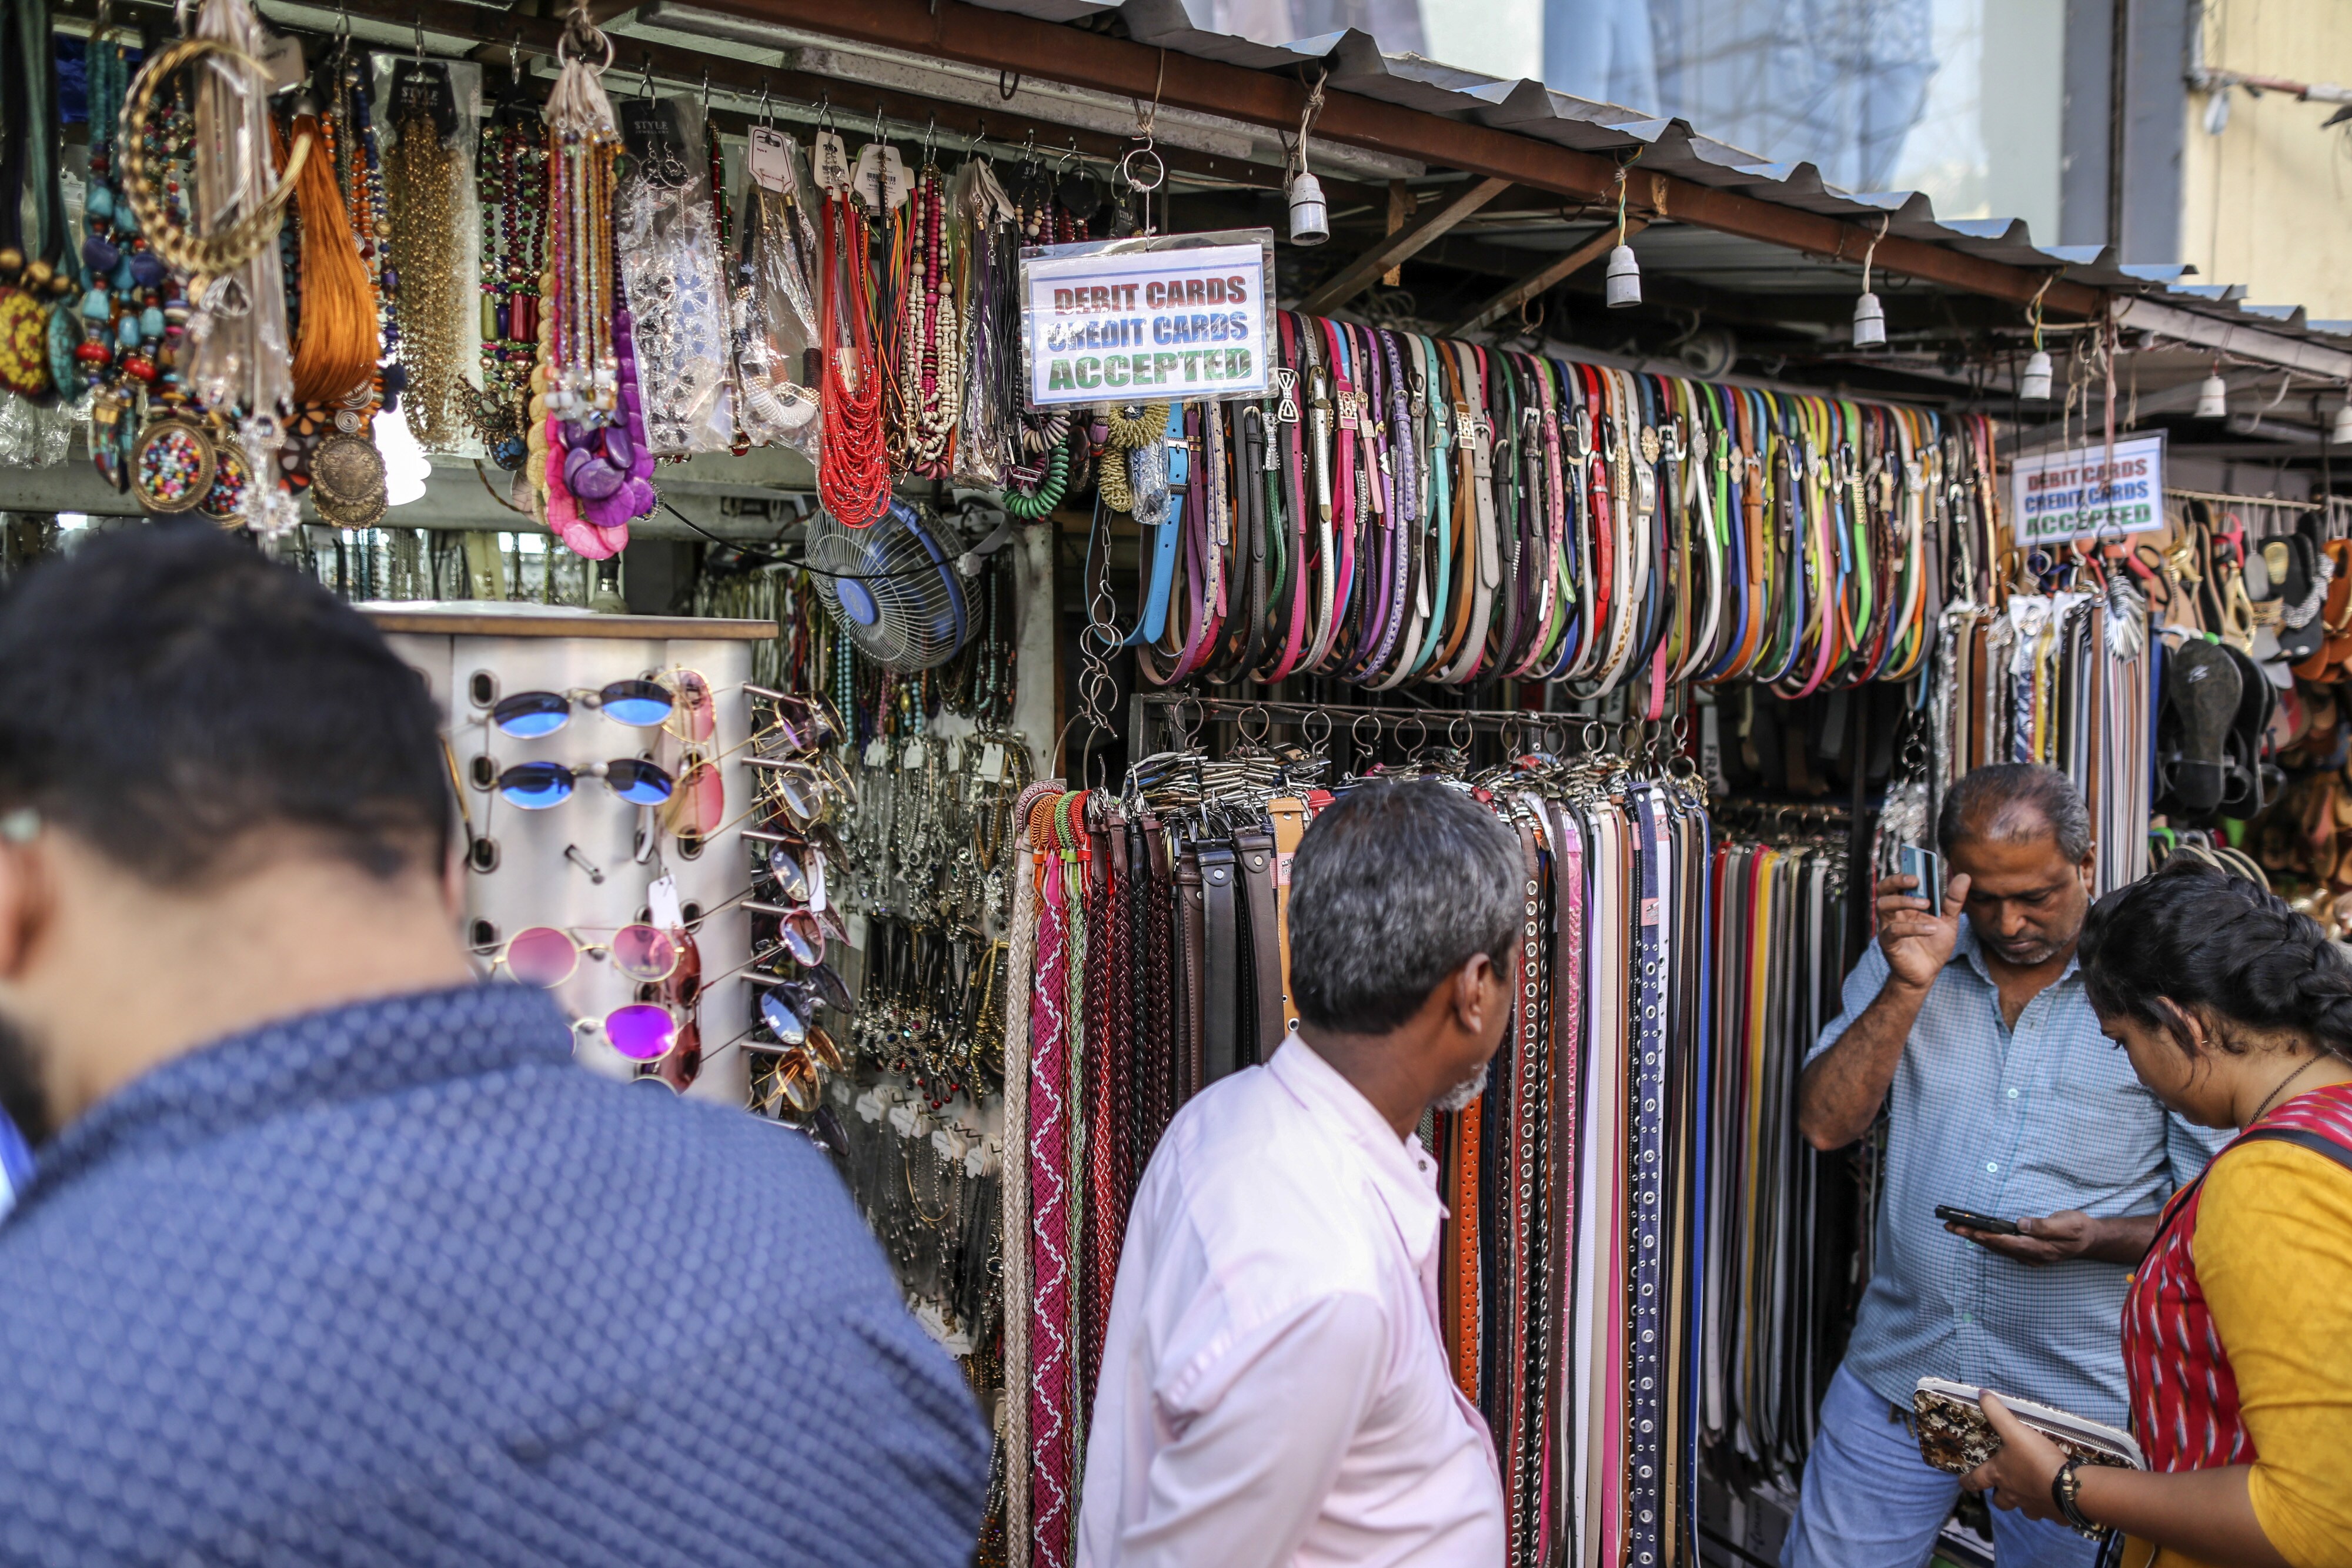
Penetration in tier-2 and tier-3 towns is “pretty low and people have aspirations over there,” Prasad said. This, added to the expansion in the number of point-of-sale machines installed from 1.1 million to over 4 million and the e-commerce boom, has led to increased adoption of credit cards even from smaller centres, he added.
The move into smaller towns and cities has not hurt the average spends per card either. Despite 58 percent of incremental cards going to tier-2, tier-3 towns, average spends have risen.
“The average spend per card has gone up to Rs 1,44,000 in 2019 compared to 1,40,000 per card in 2018,” Prasad said, referring to data for the industry as a whole. What matters is the number of times you transact and swipe your card, he added.
Is there reason to believe that this expansion could lead to increased delinquencies? Prasad does not believe so.
Terming SBI Cards as an “algorithm-driven mathematical” company, Prasad said that all aspects of a consumer are analysed before approving cards. Models around a cardholder's income, debt, cash flows are all put to use before a credit card is approved, Prasad said.
“SBI Cards is also tapping into its parent company State Bank of India's vast database. We are looking at 16 million customers, after the customers' consent. We have 'carded' about 2 million,” he said.
SBI Card's initial public offering went live today with the company already raising Rs 2,769 crore from anchor investors. Shares have been allotted at the offer's upper price band of Rs 755 apiece, according to a regulatory filing. There are 12 mutual funds among the 74 anchor investors, who have been allocated 3.66 crore shares and its value stood at Rs 2,768.55 crore.
The managing director expects the company's net interest margin to settle around 14-15 percent going forward, similar to that of its peers.
According to Prasad, the company should not be viewed as a lender, even though SBI Cards, as a non-bank lender, gives out credit on its own books. Nearly half of its income comes from the interest it earns on “revolving credit” or EMI schemes offered by it. The remaining half comes from fee.
Also Read: SBI Cards IPO: Is The Frenzy Justified?
Prasad says that SBI Cards' business model is unique and should be looked at it as such. Valuing the company using price-to-earnings rather than the price-to-book, which is typically used for lenders, is more appropriate, he believes.
When asked about growth, he said the second half of the year should be stronger than the first half. The company has mopped up Rs 725 crore in the first half and Rs 1,161 crore of profit in the first nine months of FY20. "Second half of India is always a busy season.”

-
The Economic Imperative: Analysing The Material Driving Force Behind India-Canada Strategic Reset

This economic complementarity is further reinforced by deep institutional investment ties and talent mobility, which form the bedrock of the bilateral framework.
-
Medicine Pricing: Where Must Profit Stop?
India must confront excessive margins, hidden incentives and regulatory gaps that threaten the integrity of medicine.
-
Why Amazon And Flipkart Are Struggling To Beat Meesho In India's Smaller Cities
With 274 million users and lowest-cost logistics, Meesho is defending its value commerce crown against giants like Amazon and Flipkart.
-
High US Salaries, No Green Card Certainty: The Financial Calculation Facing Indian H-1B Families
The suspension of PERM processing at eight technology employers does not cancel existing H-1B visas. What it does is force a question many Indian families have been avoiding: is the US salary worth tying your career and family plans to one employer?
-
Swiggy vs Eternal: Food Delivery's Two Rivals Are No Longer In The Same Race
Eternal is building a private AI assistant, dark.ai. Swiggy is still working out how to make Instamart pay, with an operating loss of Rs 895 crore in the July-September quarter while Blinkit stayed profitable.
-
Where You Live Shapes How You Get To Work | The Reason Why
Two-wheelers are the most popular way to get to work in India, accounting for nearly 43% of workplace commutes.
-
Unhedged Position: Can India See An Indonesia-Style Time Correction?
The Nifty is trading below levels it first clocked in 2024. Is there, then, as I have suggested in the headline, potential that the current time correction drags on painfully for the next three-five, even ten years?
-
Navigating Friction And Energy Realities: An Analysis Of Marco Rubio's October Visit To India
Occurring at a critical juncture marked by stalled trade negotiations and escalating geopolitical pressures over global energy supplies, the visit offers a profound window into modern US-India relations.
-
India Exports Capital. Why Not Export Trusteeship?
The big question, then, is whether India can build an institution that global borrowers, investors, banks, and lawyers can trust, even without an Indian connection.
-
France's Economy & Politics Are In Crisis | The Reason Why
Let's look at how the French economy and politics evolved under Nicolas Sarkozy, Franois Hollande and Emmanuel Macron.










