Page Industries: Bull Vs Bear Case
Two of the top international research firms have contrasting views on Page Industries Ltd.
UBS has initiated coverage with a 'buy' rating on the manufacture, distribution, and marketing of the Jockey brand in India, citing double-digit revenue growth in the medium-term.
"We do not see major downside risk from the current level as demand and inventory have started to improve," the research firm said in a March 15 note. UBS has a target price of Rs 44,000, implying an upside of 28.67%.
Citi Research has maintained a 'sell' rating on the stock as it expects demand momentum to remain subdued (volume decline is relatively higher in athleisurewear compared to innerwear).
Citi has set a target price of Rs 33,800 apiece, implying a downside of 2.58%.
Bull Vs Bear
UBS
Strong growth potential in the innerwear market. Page Industries expects the Indian men's innerwear market to have a 10% revenue CAGR in FY20–25 and reach $3.1 billion by FY25, driven by formalisation, as the market is still dominated by small, unorganised brands.
UBS expects Page to be a key beneficiary of formalisation, given its strong brand recall and wide distribution network. Additionally, innerwear demand has been impacted by subdued consumer demand for the past 12–16 months, and the research firm expects it to improve with lower inflation and improved consumer spending.
"As per management, demand is gradually picking up in Tier 2/3 cities with an encouraging mass-market trend, which could benefit Page," the research firm said in the note.
UBS estimates that margins will reach pre-pandemic levels. Innerwear company margins were impacted by higher discounts and volatile raw material prices for the past few quarters.
With a demand uptick (management indicated that degrowth has stopped), Page is seeing a gradual inventory correction and is approaching an optimum level.
This will increase full-priced sales, improving margins. Management also expects stable raw material prices, providing further margin support.
"We expect Page's Ebitda margin to improve 231 bps to 21.1% in FY26 (vs. FY20)," it said.
Citi Research
The aspiration of Rs 8,000 crore in revenue is likely to get pushed to FY28E vs. FY27E earlier, and new customer acquisition in men's innerwear (by virtue of premiumisation) is subdued currently as customers likely perceive Jockey's products do not offer value for money anymore (have become too pricey).
"However, the aspiration for the Jockey brand is intact, and the company has not witnessed any loss of shelf space," it said in a March 18 note.
Page Industries does not compete in the performance wear category. In comfort wear, while there are many new entrants, the current volume decline is temporary in nature as Page Industries products offer much more features.
Kids Wear: There is no established national player in this category, and Page Industries is trying to address this gap; by slightly changing the sales organisation and distribution for kid's wear.
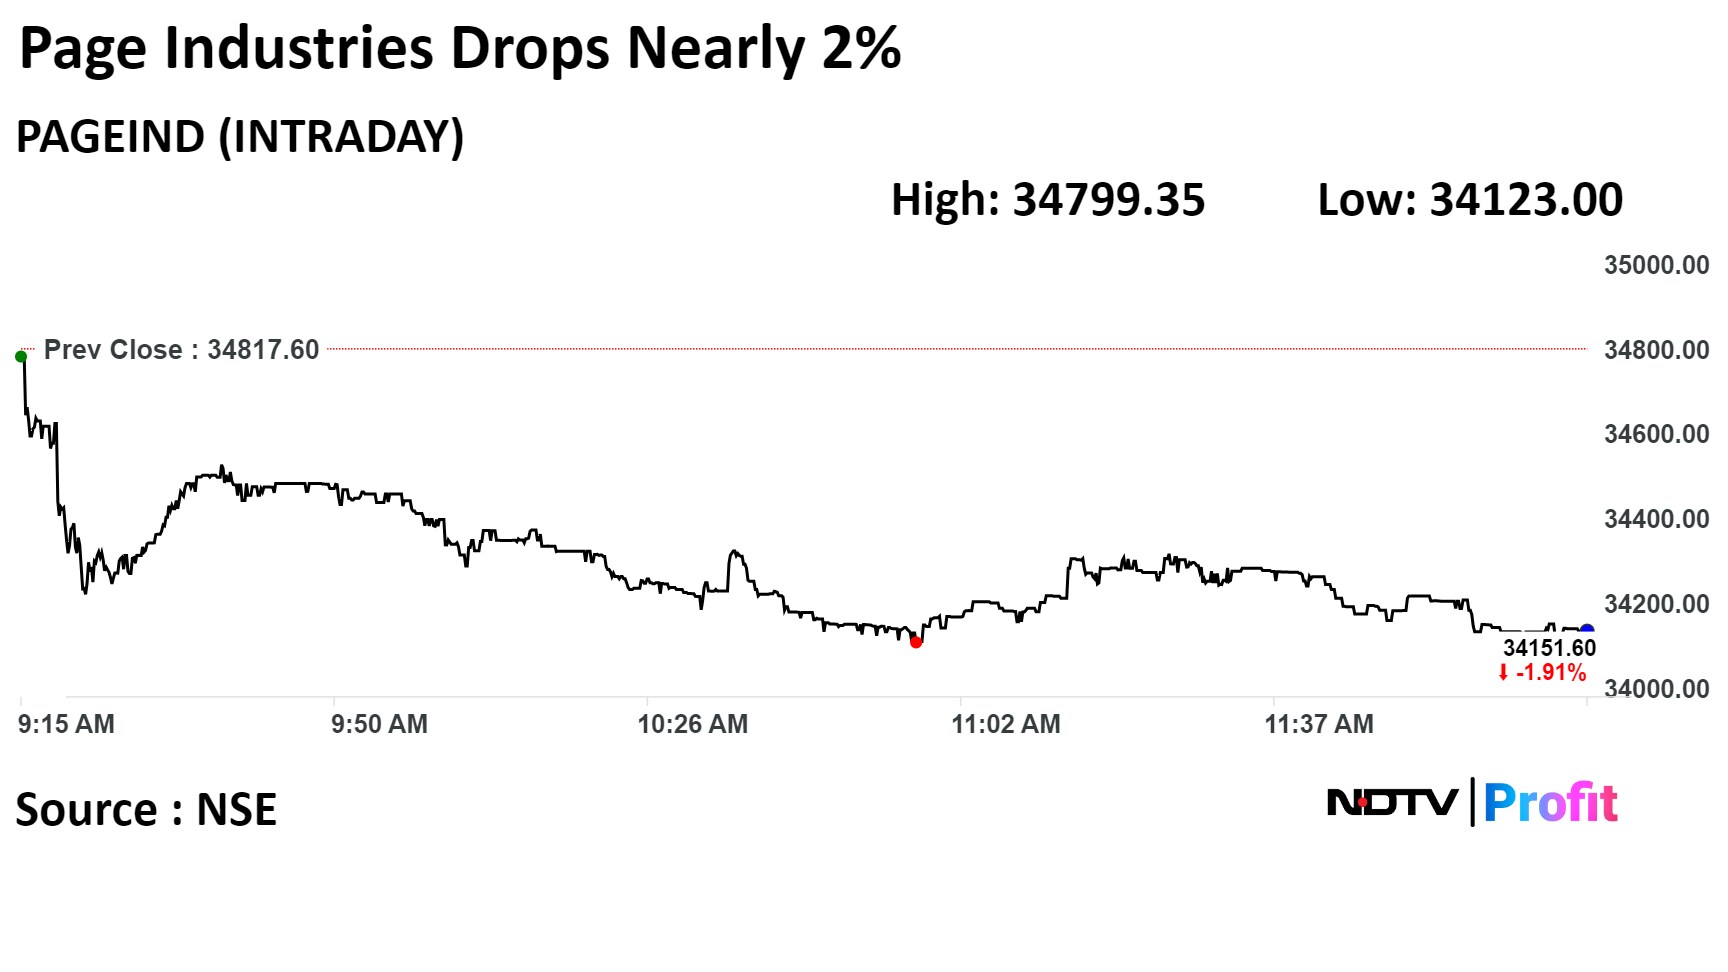
Shares of Page Industries fell as much as 1.99% at Rs 34,123 apiece. The scrip is trading at 1.86% lower at Rs 34,168.40, compared to a 1.05% decline in the benchmark Nifty 50 as of 12:10 p.m.
Of the 24 analysts tracking the company, 12 maintain a 'buy', six recommend a 'hold' and six suggest a 'sell', according to Bloomberg data. The average of 12-month analysts' price target implies a potential upside of 14.1%.

-
Indians Are Travelling, But Not Every Journey Is A Holiday | The Week In Whys

Pilgrims, patients and working women are the real travellers, and the system hasn't quite caught up with them.
-
Getting To Work Costs Women More | The Reason Why
It is not just about women paying more than men. It is about women paying much more in cities than in villages.
-
AI Bias In Investing Cannot Be Eliminated, But It Can Be Governed
Framing is a particularly important example as identical financial information presented in terms of gains rather than losses can lead an LLM to reach a different assessment.
-
Joining The Dots | Dark Skies, Steady Diya: Why Hope Holds This Diwali
With war, a weak rupee and foreign outflows weighing on sentiment, policymakers at the NDTV World Summit and market veterans at NDTV Profit Ignite: Diwali Edition offered the same advice: stay invested and filter out the noise.
-
The Curious Case of Equitas Small Finance Bank And A CEO Who Quit For Stock
PN Vasudevan believes persistent investor concerns over a perceived conflict of interest had become a governance overhang on Equitas Small Finance Bank's stock, even as the lender improved profitability and asset quality.
-
Talking Points This Week: AI Cash Burn, A Tiger Comeback And An India That Still Finds Its Own Path
India is not immune to higher oil or tighter global liquidity, yet its earnings base is broader, its domestic policy levers are still available.
-
Foreign Investors Own Half Of HDFC Bank and ICICI Bank. An LTCG Cut Could Matter Most Here
Foreign portfolio investors have US$115 billion parked in HDFC Bank, ICICI Bank. If the government cuts long-term capital gains tax, Jefferies says returning foreign money could land here first.
-
'Never Seen This Level Of Negativity': Sandeep Tandon Says The Next Rally May Be Closer Than You Think
Veteran investor Sandeep Tandon says foreign selling is easing, large-caps are due a comeback and mid-caps are crowded, while he turns positive on gold, power and pharma this Diwali.
-
Indians Stay With Family, Not In Hotels | The Reason Why
India still lacks enough clean, reliable and affordable hotels for budget-conscious travellers.
-
The Economic Imperative: Analysing The Material Driving Force Behind India-Canada Strategic Reset
This economic complementarity is further reinforced by deep institutional investment ties and talent mobility, which form the bedrock of the bilateral framework.










