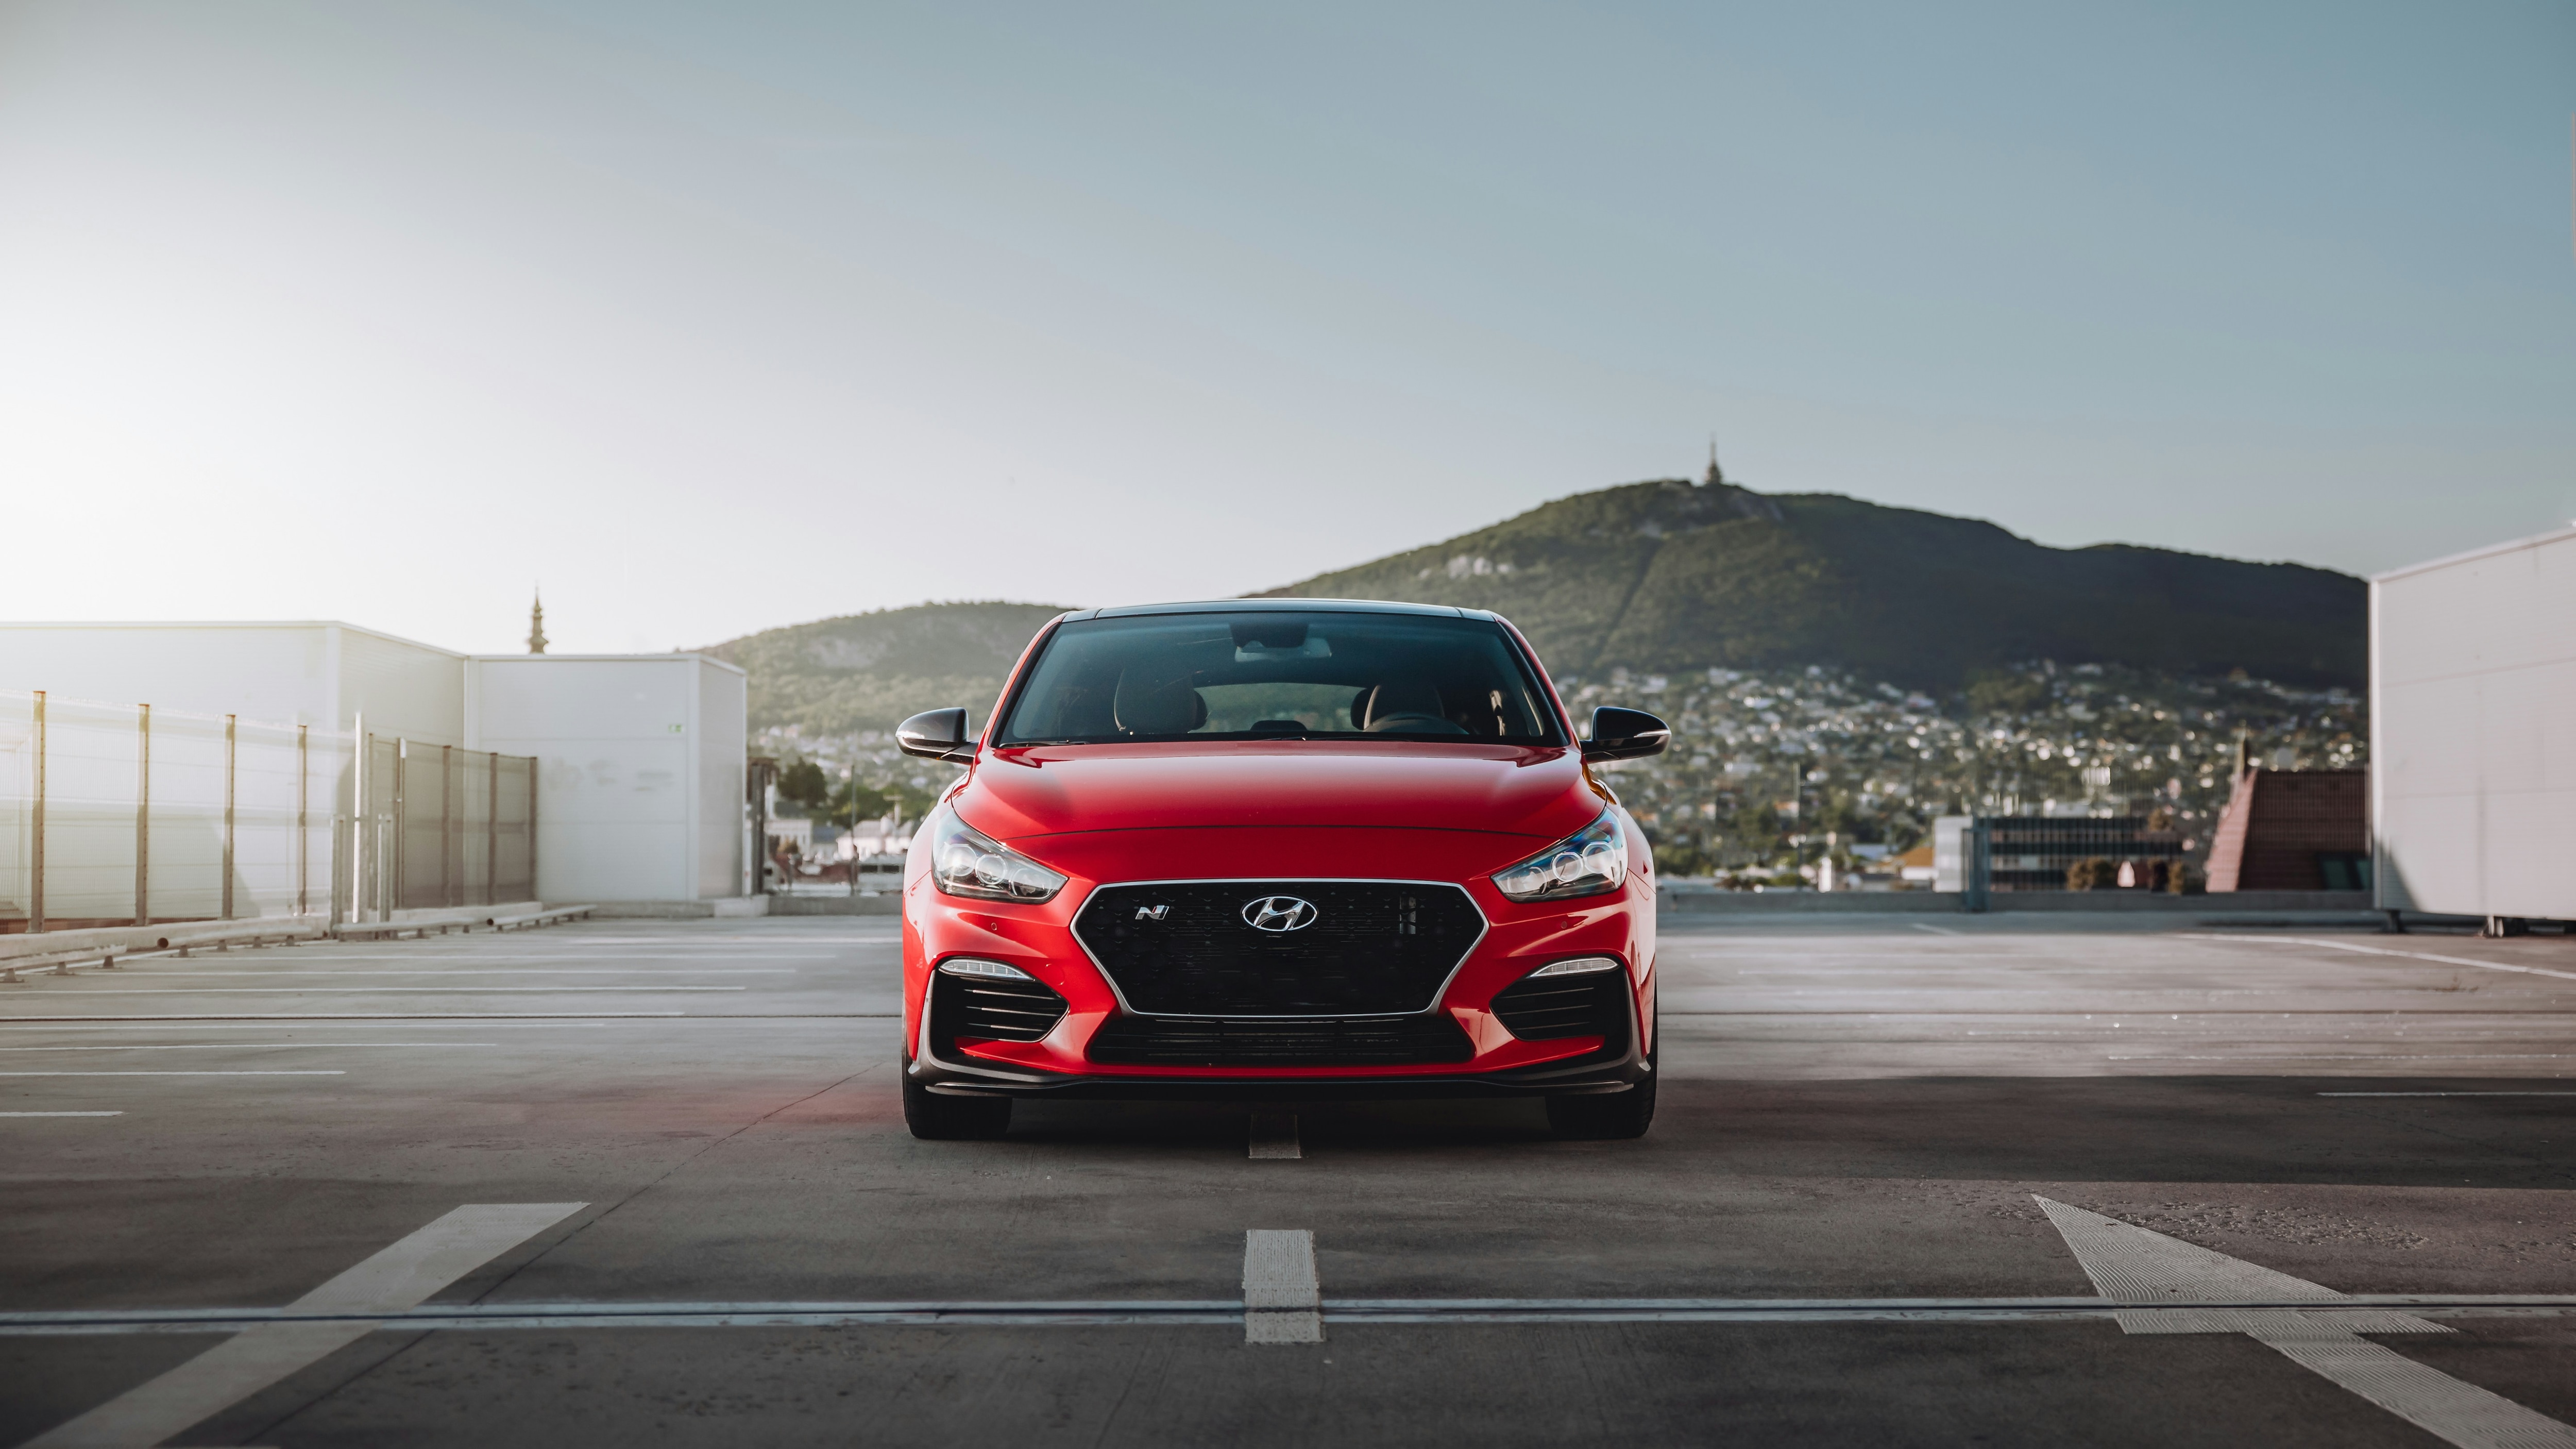
Nuvama has initiated coverage on Hyundai Motor India Ltd. with a 'buy' rating, setting an ambitious target price of Rs 2,955, with a 4% upside. The positive view is driven by the company's strong market position as India's second-largest passenger vehicle original equipment manufacturer and its promising product pipeline, which includes 26 new models and refreshes.
Nuvama anticipates double-digit revenue growth of 11% and Ebitda margin expansion of 11% to 12% over financial year 2025 to 2028, backed by a rising share of sunroofs, Advanced Driver-Assistance Systems, and premiumisation across its portfolio.

-
 Indian Markets Turning Corner After Two Tough Years, Says Sandeep Tandon
-
 NDTV Profit Ignite 2026: Experts See Opportunity In Equities, Stay Bullish For Long-Term
-
 Buy Right, Sit Tight Does Not Work for Individual Stocks, Says Dinshaw Irani
-
 'Worst Is Behind': Quant MF Sees Market Bottom, Flags 'Extreme Euphoria' In Midcaps
-
 India's Mutual Fund Industry Could Become A $1 Trillion Opportunity, Say Fund Managers
-
 'Foreign Investors Are Baraatis': Raamdeo Agrawal's Take On LTCG Tax
-
 Stay Invested Through Market Cycles: Raamdeo Agrawal at NDTV Profit Ignite
-
 Ramesh Damani Remains Bullish On India For Next 20-30 Years, Sees Bargains Amid Market Weakness
-
 CAS Came After A Long Consultation Process: SEBI Chairman Tuhin Kanta Pandey AT NDTV PROFIT IGNITE
-
 Aim To Cut FPI Onboarding Time From Mth To Five Days: SEBI Chairman Tuhin Kanta Pandey AT NDTV PROFI
Market Leadership And Product Strategy
Hyundai Motor India's notable market position is a key highlight of Nuvama's report. As a subsidiary of Hyundai Motor Co., the company has consistently delivered strong sales performance. The company plans to launch 26 new models and refreshes by financial year 2030, including six electric vehicles.
Also Read | Layoffs Are Rising In Tech, But These Skills Are Helping People Unlock Better Pay
This signals a strong commitment to innovation and market expansion. Nuvama points out that the next 18 months will be particularly active, with a new compact SUV, a micro E-SUV, and a micro E-SUV facelift expected to drive market share gains in both SUVs and premiumisation.
Turbocharging Launches And Distribution Network
Nuvama emphasised Hyundai Motor's successful track record in launching new models, which has enabled the company to recover product development costs within four years. This ability to quickly monetise new products is a significant competitive advantage.
The company is an extensive third-largest global mass-market player with revenue of $29 billion in FY24, presence in 200-plus countries, and 40-plus models. It provides a robust global distribution network.
Global R&D spending at 2.5% of revenue over the past four years further strengthens HMI's ability to offer the latest automotive technology. Nuvama expects export volume and revenue growth to improve, driven by continued growth in Latin America and Africa, and recovery in Asia and the Middle East.
Financial Outlook And Valuation
Nuvama forecasts the company will achieve an average Return on Invested Capital of 57% and a strong Free Cash Flow generation of Rs 9,430 crore by fiscal 2025 to 2028. The brokerage projects a 9-12% growth in revenue over the same period as well, with an Ebitda margin expansion of 11% to 12%.
While Nuvama's outlook is largely positive, the report also highlights key risks. These include slower-than-expected domestic and overseas growth due to muted demand, market share pressure from new product failures or competitive pricing. It also addressed margin pressures in fiscal 2026 due to higher discounting. Despite these potential headwinds, the brokerage sees strong fundamentals and strategic initiatives that position the company for growth.
Essential Business Intelligence, Sharp Market Insights, Practical Personal Finance Advice, Daily Fuel, Gold and Silver Prices and Latest Stories — On NDTV Profit.